myspyoptions.com

Categories
Finance Options Trading

Selling Puts: How It Works, Risks & Strategies

A selling puts strategy involves receiving premiums in exchange for agreeing to buy 100 shares of a stock per standard put at the strike price in case the assignment happens. If the stock stays above the strike price at expiration, you generally keep the premium. Unlike buying a put, which gives the buyer the right to sell the underlying asset within a specific period, selling a put obligates the seller to buy the underlying asset at a specific price if assigned. Selling puts provides credit up front, but a sharp drop in the stock can cause a large loss.

Traders usually sell puts when they are neutral to bullish because the put seller gains when the underlying asset does not fall below the strike price. This guide covers how selling puts works, what you can gain or lose, and which mistakes to avoid.

Key Takeaways

  • Maximum profit: The premium received, before fees and costs.
  • Maximum loss: (Strike price − premium received) × 100 per standard contract, if the underlying asset falls to zero.
  • Break-even: Strike price − premium received.
  • Outlook: Neutral to bullish.
  • Assignment: If assigned, you buy 100 shares per contract at the strike. If not, you keep the premium and never own the stock.
  • Collateral: The seller must have adequate collateral, which could be cash or margin, depending on the broker.

What is Selling a Put Option?

Put option writers, or put sellers, are paid a premium for taking on the obligation to buy the underlying asset at a specific price if the option is exercised and assigned. The seller’s best-case scenario is for the option to expire worthless, allowing them to keep the full premium. The worst case loss is substantial but not unlimited.

Traders can sell out-of-the-money (OTM) put options when they believe the option will expire worthless, but a sharp decline in the stock price can result in substantial losses. If you sell put options but do not want to own the stock, you can allow the option to expire worthless or buy it back to close the position before expiration.

How Does Selling Puts Work?

When selling puts, three terms are important: strike price, premium, and expiration.

Strike Price

The strike price is the fixed price at which the seller is obligated to purchase the underlying asset if the option is exercised and the seller is assigned. For example, with a put option that has a strike price of $100, the seller is obligated to buy the stock at $100 per share if assigned.

Premium

The premium is the amount the buyer pays to the seller for taking on the option obligation. If you sell a standard 100 share contract for $2 per share, you receive $200 up front, before fees and costs.

Expiration

All options expire at a certain date. US equity options are typically American style, meaning that they can be exercised at any time up until they expire. Some index options may be European, which means that they can only be exercised at expiration. Most in-the-money options will be exercised on their own when they reach the expiration date, but review your broker’s rules and applicable exercise procedures.

Early Assignment Risk

A short put can be assigned before expiration because the holder of an American-style option can exercise the option early. If assigned, the seller must buy back the underlying shares at the strike price, even if the stock price is lower. Assignment notice may come later and hence, monitor positions that may be assigned and ensure sufficient cash or margin to cover the obligation.

What is the Profit and Loss From Selling Puts?

When selling a short put, it is important to understand the potential profit and loss, as the premium may be relatively small, but the risk can be high.

Maximum Profit

The maximum gain possible from selling puts is simply the premium received. For instance, if you sell a put for a premium of $2 on a 100 share contract, your maximum gross profit will be $200 if the put expires worthless.

Maximum Loss

The maximum loss for selling a put depends on the movement in the underlying stock. If the stock price falls to zero, the maximum loss incurred in selling the put is $98 per share ($100 strike price − $2 premium), or $9,800 per 100-share contract.

Max Loss = (Strike Price – Premium Received) x 100

Break-Even Point

The break-even point for a short put is:

Break-Even = Strike Price – Premium Received

For example, a $100 strike put sold at a $2 premium has a break-even price of $98. If the stock finishes above $98 at expiration, the seller makes a profit; at exactly $98, the position reaches break-even; below $98, the position moves into a net loss.

Worked Example: Selling a $100 Put

Suppose you sell one put contract with a $100 strike price and receive a premium of $2 per share ($200 total per 100-share contract).

Stock Price at Expiration Result Before Fees and Costs
$120 $200 profit; option expires worthless
$105 $200 profit; option expires worthless
$100 $200 profit at expiration, subject to pin risk and assignment procedures
$98 Break-even point
$95 $300 net loss
$80 $1,800 net loss
$0 $9,800 maximum loss

Cash-Secured Puts vs. Naked Puts

When selling puts, your broker requires collateral to ensure you can fulfil your obligation if assigned.

Feature Cash-Secured Put Naked Put (Margin)
Collateral Type 100% cash in account Margin buying power / equity
Capital Requirement Strike price × 100 shares in cash (e.g., $10,000 for a $100 strike price) Broker margin formula (commonly around 20% of the underlying’s value, minus the OTM amount, plus premium, but it varies by broker)
Risk Profile Lower leverage, defined max cash outlay Higher leverage, potential margin calls during market crashes

The Role of Volatility and Theta Decay

Understanding options Greeks, particularly implied volatility and theta, can help you assess put selling opportunities:

  • Implied Volatility (IV): Short puts generally benefit if volatility falls (IV crush), as option prices decline. But the increase in implied volatility is not necessarily better for a naked put writer than it is for a cash-secured put writer, as higher IV also equals higher option values and margin requirements.
  • Theta Decay: Options lose value over time as they approach expiration. As a put seller, you want time to work in your favour.

Put Selling Strategies: Strike Selection, Rolling, and The Wheel

To maximise consistency, experienced traders apply structured strategies:

  • Strike and Expiration Selection: Typically, many traders sell 30-45 days to expiration, where theta decay accelerates while picking the strikes around 0.15-0.30 delta where you would actually feel good owning the shares.
  • Rolling a Position: When a stock drops below your strike price, you can “roll” the put by closing the existing contract and opening a new one with a lower strike and/or later expiration.
  • The Wheel Strategy: A popular systematic approach where you start by selling cash-secured puts. When assigned, you own the shares and then begin selling the covered calls until they are called away, then repeat.

What are the Most Common Mistakes When Selling Puts?

Although selling puts generates premium income, the seller must be prepared to purchase the underlying shares if assigned. Proper planning and position sizing can help reduce the risk of avoidable mistakes. Here are five common mistakes to avoid when selling puts:

  1. Selling puts as easy money: Many investment newcomers sell puts without realising they have an obligation to buy the stock. If the stock plunges, you can lose a lot.
  2. Failing to develop a plan for risk management: If you sell a put option, think in advance how you would respond in case the stock falls. Establish the criteria for either closing the position, accepting the assignment or managing losses.
  3. Far OTM Puts: Far out-of-the-money options have a low chance of being assigned, but are not riskless. A sudden sharp decline can immediately put the option into the money.
  4. Break-Even Point and Market Conditions: Do not sell a contract without knowledge of the market fundamentals of the underlying asset and without knowing the break-even point.
  5. Over-Committing Capital: Selling many puts leads to a great downside during market declines. Make sure you have enough capital available.

Conclusion

Selling puts allows the trader to collect premium payments and acquire an asset at a predetermined price. This strategy is most efficient when a trader is aware of their duties, determines the break-even point, controls the market volatility and has enough capital.

For practical options education, market perspectives, and trading alerts, visit MySPYOptions to build a clearer understanding of selling puts and other strategies.

Risk Disclaimer: Trading options carries significant risk and is not appropriate for all investors. Selling put options can involve heavy losses, even losses of thousands of dollars per one put contract, and margin calls may rise when market trends become unfavourable for the investor’s positions. Make sure to review the Options Clearing Corporation (OCC) Characteristics and Risks of Standardised Options document before trading. The following information is provided for educational purposes only and is not intended for investment advice.

FAQs About Selling Puts

Is selling puts a bearish or bullish strategy?

Generally, selling put options is a bullish strategy because the trader can profit if the price of the asset remains above the strike price of the put sold.

What is the maximum profit for selling puts?

The maximum profit is defined by the premium received when opening a put option position and can be achieved when the option becomes worthless.

Can selling puts involve losses?

Yes, selling puts can be very dangerous since a put seller can lose a lot of money due to the drop in the value of the underlying asset below the strike price.

Can a put seller close a position early?

Yes, A trader can close a short put position before expiration by buying back the same put option to close the position.

Is selling puts risky?

Yes, there is always high risk involved in selling puts due to the possibility of losing a lot of money on the position during the period the underlying asset declines.
Categories
Finance Options Trading

Selling Put Options Explained

What does selling puts mean? Selling puts means selling a put option and collecting a premium upfront. In exchange, you accept an obligation: if the option is exercised and you’re assigned, you must buy the underlying at the strike price. Your profit is capped at the premium, while your downside can be large.

  • You get paid upfront, but you take on an obligation to buy at the strike.
  • Maximum profit = the premium. Breakeven = strike − premium.
  • Maximum loss ≈ (strike − premium) × 100 per contract, if the price falls to zero.
  • One contract usually means 100 shares, so the exposure is bigger than it looks.
  • Only sell a put at a price you’d genuinely accept, in a size your account can handle.

What does selling puts mean?

When you sell a put option, you give the buyer the right to sell you the underlying at a set strike price. You get a premium for that. Simple to say, but the real story starts after the premium lands in your account.

  • Put buyer: pays a premium and gets a right.
  • Put seller: receives a premium and takes on an obligation.

For standard U.S. equity and ETF options, one contract covers 100 shares. Sell one $100 put, get assigned, and you’d generally have to buy 100 shares for $10,000, before counting the premium. FINRA describes it the same way: a seller who opens a short put accepts the obligation to buy at the strike if assigned.

Why would someone sell a put?

Usually because their outlook is neutral to moderately bullish, and for one of two reasons:

  1. To collect the premium if the underlying stays above the strike.
  2. To potentially buy the underlying at a chosen price if it falls and they’re assigned.

Selling puts isn’t necessarily a bet on a big rally. You might simply think the price will hold above your strike.

How does selling put options work?

Here’s the sequence, in five steps.

1. Pick the underlying. Choose something you understand and would be willing to own, such as SPY, QQQ or a liquid stock. Decide this before you look at premiums.

2. Choose a strike. Suppose QQQ trades at $500 and you’d be comfortable owning it at $480. You might look at the $480 put. A lower strike leaves more room for the price to fall before you’re in trouble, but it generally pays less.

3. Choose an expiration. This sets how long you’re exposed to price moves, volatility and assignment. Weigh time to expiry, implied volatility, upcoming events and how much capital you’re tying up.

4. Sell the put. You collect the premium immediately. A $4 premium × 100 = $400, which is your maximum gross profit if the put expires worthless.

5. Manage it. You don’t have to hold to expiration. Depending on your plan and broker, you can buy it back, let it expire, roll it to another strike or date, or accept assignment.

In short, you’re being paid upfront to accept the possibility of buying at the strike.

Selling puts example (hypothetical SPY trade)

The prices below are made up to show the mechanics.

Say SPY trades at $600. You sell one $580 put for $5.00.

Item Example
SPY price $600
Put strike $580
Premium $5.00
Contracts 1 (100 shares)
Premium received $500
Potential purchase obligation $58,000
Breakeven $575

The math:

  • Premium: $5 × 100 = $500
  • Potential obligation: $580 × 100 = $58,000
  • Breakeven: $580 − $5 = $575

What are the possible outcomes when you sell a put?

Using that same trade, there are three zones at expiration:

  1. SPY above $580 (say $590 or $620). The put expires worthless and you keep the full $500. It doesn’t matter how far above the strike SPY goes, because your profit never grows beyond the premium.
  2. SPY between $575 and $580. You’re likely assigned and buy at $580, but your effective cost is $575 after the premium, so you’re still slightly ahead.
  3. SPY below $575 (say $550). You’re assigned at an effective $575 for shares now worth $550, a loss of ($575 − $550) × 100 = $2,500. The premium softened it but didn’t erase it.

What are the maximum profit, breakeven and maximum loss?

  • Maximum profit: the premium. Sell one put for $5 and the most you can make is $500.
  • Breakeven: strike − premium. In our example, $580 − $5 = $575. Above it, the position is profitable at expiration; below it, you’re losing money.
  • Maximum loss: if SPY fell to zero, you’d lose about ($580 − $5) × 100 = $57,500, ignoring fees.

That’s a wide gap between a $500 possible gain and a $57,500 theoretical loss. The Options Industry Council describes short puts the same way: capped gain, potentially substantial loss. The premium is never a substitute for risk management.

Selling puts vs buying puts

Factor Buy a put Sell a put
Cash flow at open Pay premium Receive premium
Typical outlook Bearish or hedging Neutral to moderately bullish
Maximum profit Potentially large Limited to premium
Maximum loss Premium paid Potentially large
Time decay Usually works against you Usually works for you, all else equal
Obligation None Must buy if assigned
Main purpose Downside exposure or hedge Premium or planned entry

A put buyer wants the price to fall. A put seller generally wants it to stay above the strike, or at least not fall far past breakeven.

Selling puts vs cash-secured puts vs naked puts

  • Selling a put describes the transaction.
  • A cash-secured put is a short put backed by enough cash to buy the shares if assigned. (We cover it in detail in our cash-secured puts guide.)
  • A naked put is a short put without full cash reserved. It typically relies on margin, with different requirements and different risks.

They aren’t the same risk profile. Cash-secured means cash is set aside; naked means you’re relying on margin. Your broker’s approval level and margin rules decide what you’re allowed to do, and those vary by firm.

The PUTS framework: a way to evaluate any short put

P: Pick something you want to own. Start with the asset, not the premium. If you wouldn’t be happy holding it after a drop, stop.

U: Understand the market. Look at the trend and structure: moving averages, RSI, MACD, VWAP, volume, support and resistance, and recent volatility. Technicals don’t predict anything for certain, but they give your strike some context.

T: Target a strike. Base it on the price you’re willing to pay. Consider distance from the current price, implied volatility, delta, support levels and the assignment price.

S: Size the position. This is where beginners slip. A $500 QQQ put means $50,000 of potential purchase per contract, so work out the total exposure before selling more than one.

The best strike is rarely the one with the highest premium. It’s the one where price, outlook and size all make sense together.

How do the Greeks affect selling puts?

  • Delta: how much the option’s price may move for a $1 move in the underlying. Traders often use it as one input when choosing strikes.
  • Theta: time decay. For a short put it generally helps the seller, all else equal.
  • Vega: sensitivity to implied volatility. If IV rises, the put’s value can rise, which works against you.
  • Gamma: how fast delta changes. It matters most near expiration and close to the strike.

Theta helps only if nothing else overwhelms it. A sharp price move or a volatility spike can easily outweigh a few days of decay.

How do you choose a strike when selling puts?

The most common beginner question is “which strike pays the most?” The better one is “at what price would I genuinely want to own this?” Then run through five checks:

  1. Desired entry price: what would you be comfortable paying?
  2. Trend: is it trending, consolidating or breaking down?
  3. Support: is the strike near a meaningful level?
  4. Implied volatility: is the premium high because the market expects a big move?
  5. Position size: can you handle assignment comfortably?

A lower strike gives more cushion but pays less. A higher strike pays more but raises your potential purchase price. There’s no universal best answer.

Can you sell puts on SPY and QQQ?

Yes. Both have very active options markets, which is why they’re popular. But the 100-share multiplier still applies.

If QQQ trades at $500, one $480 put creates a potential purchase of 100 × $480 = $48,000. That doesn’t mean you’d lose $48,000; it means you need to know the capital commitment before entering. Size your position on the potential assignment, not on the premium. MySpyOptions’ SPY and QQQ training covers this kind of sizing alongside strategy, risk management and live sessions.

What happens if a put you sold is assigned?

Assignment means you have to buy the underlying at the strike price, generally 100 shares per contract. FINRA explains it this way for short equity puts. For American-style equity and ETF options, assignment can happen before expiration, so “I’ll decide at the last minute” isn’t a plan.

Assignment isn’t automatically bad. If you chose the strike because you wanted the shares at that price, it just means your plan triggered. The real problem is selling a put on something you don’t actually want to own.

Can you roll or close a short put early?

Yes, and many traders do rather than hold to expiration.

  • Buy to close: buy the put back to end the obligation. That might lock in a profit or cut a loss.
  • Roll: close the current put and open another at a different strike, expiration or both. Rolling can buy time, but it can also push a losing idea further out and add risk.
  • Let it expire: if it’s out of the money, it usually expires worthless and you keep the premium.

Decide your rules before you enter, such as when you’d take profits, when you’d cut, and under what conditions you’d roll. Making it up under pressure rarely goes well.

Is selling puts a good idea?

It depends on the trader. Selling puts can make sense if you:

  • have a neutral to moderately bullish view
  • would be comfortable owning the shares at the strike
  • have the capital to fund assignment
  • understand the downside and size accordingly

It may be a poor fit if you’d panic after assignment, you need the cash soon, you expect a sharp decline, or the position would be too big for your account. It’s also worth remembering that selling puts for income isn’t the same as risk-free income. The premium arrives first, but the risk comes later.

7 common mistakes when selling puts

  1. Chasing high premium. It often signals high implied volatility and a bigger expected move.
  2. Ignoring the 100-share multiplier. Always calculate strike × 100 × contracts.
  3. Selling puts on something you dislike. If assignment would panic you, skip it.
  4. Treating premium as guaranteed income. Final profit depends on where the underlying goes.
  5. Ignoring liquidity. Wide bid-ask spreads make entries and exits costlier.
  6. Ignoring catalysts. Earnings, economic data and major news can shift price and volatility fast.
  7. Oversizing. One contract can feel conservative. Ten or twenty are a different trade entirely.

A beginner’s checklist before you sell a put

  1. Do I understand what the contract represents?
  2. Would I buy 100 shares at this strike?
  3. Have I calculated the premium?
  4. Have I worked out the breakeven?
  5. Do I know the maximum potential loss?
  6. Can I fund assignment?
  7. Is the underlying liquid?
  8. Have I checked implied volatility?
  9. Have I reviewed the options chain?
  10. Does the strike make technical sense?
  11. Is the position size appropriate?
  12. What will I do if it falls sharply?
  13. Have I considered early assignment?

If you can’t answer these clearly, the trade needs more analysis.

Learn to sell puts on SPY and QQQ with MySpyOptions

Knowing the terminology is one thing. Applying it in live markets is another. MySpyOptions offers U.S. options education with a focus on SPY and QQQ, covering fundamentals, strategy execution, risk and trade management, and live market sessions. It helps connect strike choice, premium, sizing and assignment into one repeatable process. The goal isn’t to sell as many puts as possible. It’s to know when selling one fits your plan, and when it doesn’t.

Summary

Selling puts means taking a premium in exchange for an obligation to buy at the strike if assigned. It can suit a neutral-to-moderately-bullish trader who’s happy to own the underlying and has the capital and a management plan. The essentials: breakeven = strike − premium, maximum profit is the premium, and the downside can be large. Don’t sell a put just because the premium looks good. Sell it when the strike and the size are ones you can genuinely accept.

Frequently asked questions

What does selling a put option mean?

You receive a premium from a buyer in exchange for accepting an obligation to buy the underlying at the strike if you’re assigned. It’s typically used with a neutral-to-moderately-bullish outlook by traders comfortable owning the underlying.

How does selling a put option make money?

You profit when the premium you collect exceeds any losses on the position. If the underlying stays above the strike through expiration, the put may expire worthless and you generally keep the premium, which is also your maximum gross profit.

What is the breakeven price when selling a put?

Strike price minus premium received, at expiration. Sell a $100 put for $3 and your breakeven is $97, excluding costs.

What happens if you sell a put and the stock goes down?

The put can go in the money, and you may be assigned and required to buy at the strike. A big drop can produce a loss far larger than the premium.

What is the difference between selling a put and a cash-secured put?

Selling a put is the transaction. A cash-secured put is a short put backed by enough cash to buy the shares if assigned. One $500 ETF put creates a potential $50,000 purchase obligation, before the premium.

Can you sell puts on SPY and QQQ?

Yes. Weigh the strike, expiration, premium, implied volatility, liquidity, assignment risk and size. Because standard ETF options represent 100 shares, the potential assignment value can be large.

Is selling puts risky?

Yes. Your profit is capped at the premium while your loss can be substantial if the underlying falls sharply, so position size and strike choice matter a lot.

Can you sell a put without owning the stock?

Yes. Selling a put doesn’t require owning shares, but you need enough cash or margin to cover a potential assignment, depending on your broker’s rules.

Can you close a short put before expiration?

Yes. You can buy it back to close, or roll it to a different strike or date, depending on your plan and broker.

Categories
Finance Options Trading

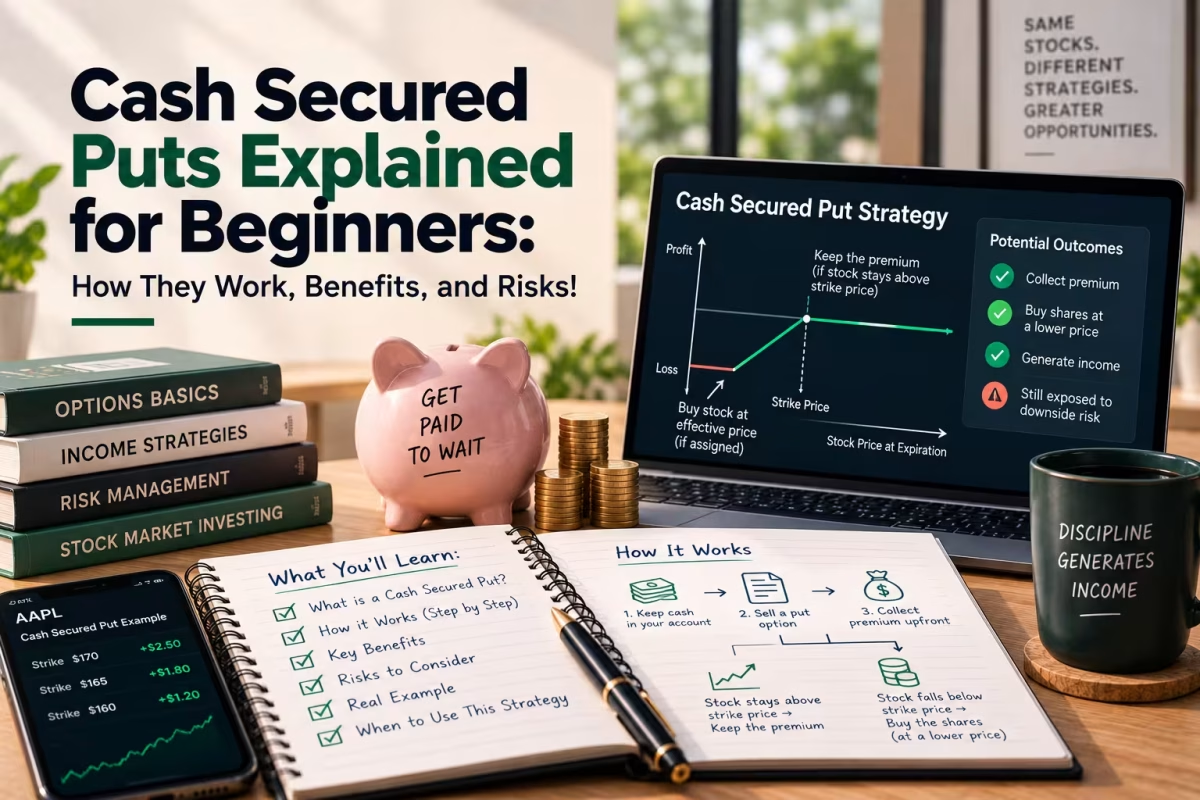
Cash-Secured Puts Explained for Beginners

What is a cash-secured put? A cash-secured put is an options strategy where you sell a put and keep enough cash on hand to buy 100 shares at the strike price if you’re assigned. You collect a premium upfront. If the option expires worthless, you keep it. If not, you buy the shares at the strike, and the premium lowers your effective cost.

  • You sell a put, collect a premium and reserve cash equal to the strike × 100.
  • Your best case is the premium. Your worst case is owning shares that have dropped a long way.
  • Breakeven = strike − premium. Maximum loss ≈ (strike − premium) × 100.
  • Only pick a strike where you’d genuinely be happy to own the shares.
  • The strategy is simple to understand, but it isn’t low risk.

What is a cash-secured put?

Cash secured puts are among the easier options strategies to get your head around. You sell a put, take in a premium, and put aside enough cash to buy the underlying if it’s assigned to you.

For standard U.S. equity and ETF options, one contract covers 100 shares. Sell a $100-strike put and you’re agreeing to potentially buy 100 shares for $10,000, before counting the premium.

The Options Industry Council (OIC) frames it as primarily a stock-acquisition strategy for a price-sensitive investor with a neutral-to-moderately-bullish view.

So the question for SPY and QQQ traders isn’t “how much premium can I collect?” It’s this: would I still be comfortable owning 100 shares at this strike if the market falls?

What does “cash-secured” actually mean?

It means the cash to cover the purchase is already sitting in your account. Here’s a small, hypothetical case:

  • Stock price: $100
  • Put strike: $95
  • Premium: $2 per share ($200 per contract)
  • Cash needed if assigned: $9,500
  • Effective cost if assigned: $95 − $2 = $93 per share

The premium trims your cost, but it doesn’t protect you if the stock drops well below $93.

How do cash secured puts work?

Every cash-secured put has three moving parts: a strike, an expiration and a premium. Here’s the process, step by step.

1. Pick something you’d want to own. This is the most important step. Suppose you’d be happy holding SPY (which tracks the S&P 500) or QQQ (which tracks the Nasdaq-100) at a certain price. That price is where you start.

2. Choose the strike. It’s the price you may have to pay. A lower strike usually means a lower premium and a lower purchase price. A higher strike usually pays more but puts you closer to the market. There’s no universally “best” strike; it depends on your target price, outlook, implied volatility, expiration and risk tolerance.

3. Choose the expiration. Shorter dated puts give the market less time to reach your strike, but also less time for your idea to play out. Longer dated puts give you more time but lock up your cash for longer.

4. Sell the put and collect the premium. Remember that premium isn’t risk-free income. It’s payment for taking on an obligation.

5. Manage the position. You can let it expire, buy it back, roll it to a different strike or date, or accept assignment. Schwab notes that a short option can be assigned before expiration, so assignment isn’t just a closing-bell event.

Put simply: you’re saying “I’m willing to buy this at this price, and I’d like to be paid for that promise.”

Cash-secured put example (hypothetical QQQ trade)

All prices below are made up to illustrate the mechanics.

Say QQQ trades at $500. You’d like to own it, but only if your effective cost is near $480. A $480 put is priced at $5.00, and you sell one contract.

Item Example
QQQ price $500
Put strike $480
Premium $5.00
Contract multiplier 100
Premium received $500
Cash reserved $48,000
Breakeven $475
Maximum profit $500

The math:

  • Premium: $5 × 100 = $500
  • Cash needed: $480 × 100 = $48,000
  • Breakeven: $480 − $5 = $475

If QQQ stays above $480 at expiration, the put likely expires worthless and you keep the $500. If it falls below $480 and you’re assigned, you buy 100 shares at $480, and your effective cost is $475 after the premium. If QQQ crashes to $400, you still paid $480 for shares now worth $400.

That’s why “getting paid to buy at a discount” is only half the story. You’re getting paid to accept the chance of buying after a drop.

What are the possible outcomes of a cash-secured put?

Using the same QQQ example, there are really three zones:

  1. QQQ finishes above $480. The put expires worthless. You keep the full $500 and don’t buy any shares. This is your best case.
  2. QQQ finishes between $475 and $480. You’re likely assigned and buy at $480, but the premium brings your cost to $475, so you’re still above breakeven. You own shares with a small cushion.
  3. QQQ finishes below $475. You’re assigned and you’re underwater. At $460, for instance, you’d own shares bought at an effective $475 that are worth $460. The premium softened the blow but didn’t stop it.

What are the maximum profit, breakeven and maximum loss?

  • Maximum profit: the premium. Sell a put for $3.00 and the most you can make is $3 × 100 = $300, if it expires worthless.
  • Breakeven: strike − premium received. A $100 strike sold for $3 breaks even at $97.
  • Maximum loss: (strike − premium) × 100. For that same trade: ($100 − $3) × 100 = $9,700, which happens only if the underlying goes to zero.

Mathematically the loss is capped because a price can’t fall below zero. In practice it can still be very large, which is why calling the strategy “low risk” without qualification is misleading. The OIC describes the maximum loss as substantial.

Cash-secured put vs buying the stock

Factor Cash-secured put Buying the stock or ETF
Goal Maybe buy lower, collect premium Own it right away
Income Premium None from the purchase itself
Upside Capped at the premium if it expires OTM Participates in gains
Downside Substantial Substantial
Ownership Only after assignment Immediate
Dividends None before assignment Yes, if paid
Capital Cash reserved Cash spent
Best for Buyers with a target price Buyers who want exposure now

The trade-off is real. If SPY jumps 8%, the stockholder captures it, while the put seller usually just keeps the premium. Cboe notes that put-writing strategies can lag in strongly rising markets.

Cash-secured put vs a limit order

A limit order says “buy this if it drops to my price.” A cash-secured put says “I’ll buy at this strike if I’m assigned, and I want a premium for committing.”

Limit order Cash-secured put
Premium received No Yes
Purchase obligation No Yes, if assigned
If price never reaches target Nothing happens You keep the premium
Flexibility Higher Lower while open

The premium is compensation for an obligation a limit order simply doesn’t carry.

Cash-secured put vs covered call vs naked put

  • Covered call: you already own the shares and sell a call against them. It’s the “own first” cousin of the cash-secured put, which is the “cash first” version.
  • Naked put: also a short put, but without full cash backing it. It relies on margin and can carry very different requirements and risks.
  • The wheel strategy: many traders sell cash-secured puts until assigned, then sell covered calls on the shares, and repeat. It’s popular, but it inherits the risks of both legs, and in a falling market you can end up holding shares at a loss.

How do I choose a cash-secured put strike?

Choosing by premium alone is the classic beginner mistake. Use the WILLING checklist instead:

  • W: Want it. Would you honestly like to own SPY, QQQ or this stock?
  • I: Identify your price. What entry price makes ownership attractive?
  • L: Look at context. Trend, support and resistance, VWAP, moving averages, volume.
  • L: Liquidity. Bid-ask spread, volume and open interest.
  • I: Implied volatility. High IV inflates premium, but only because the market expects bigger moves.
  • N: Note the risk. Cash commitment, breakeven and maximum loss.
  • G: Go only if assignment is fine. If getting assigned would bother you, the strike is wrong.

Pick the strike from the price you’re willing to pay, not from the premium that looks juiciest.

Can you sell cash-secured puts on SPY and QQQ?

Yes. Both have liquid ETF options and plenty of expiration choices, which is part of why they’re popular with retail traders. Both are worth learning through a SPY and QQQ lens.

The catch is capital. A hypothetical $500 QQQ strike × 100 = $50,000 for a single contract. That makes position sizing critical, and selling several contracts because the premium looks nice multiplies both the income and the assignment obligation.

Before you sell, ask:

  • How much cash am I committing?
  • How many shares could I be assigned?
  • Is that too big for my account?
  • What if the ETF drops 10% or 20%?
  • Would I still want to hold it?

Also check your brokerage. You’ll typically need options approval, and rules on collateral vary between firms.

How do the Greeks affect a cash-secured put?

You don’t need advanced math, but the Greeks explain the behavior:

  • Delta: the estimated change in the option’s price for a $1 move in the underlying. It’s also a rough gauge of price sensitivity.
  • Theta: time decay. For a short put it generally works in the seller’s favor, all else equal.
  • Vega: sensitivity to implied volatility. A jump in IV can raise the put’s value, which hurts the seller on a mark-to-market basis.
  • Gamma: how fast delta changes. It matters most near expiration and close to the strike.

Time decay can help you, but price moves and volatility can easily swamp it. Never judge a trade by theta alone.

What happens if you’re assigned?

Assignment means you have to buy the underlying under the contract, generally 100 shares per contract. Cboe notes that ETF options are physically settled and American-style.

If you sold a hypothetical QQQ $480 put and get assigned, you receive 100 shares at $480, with your premium lowering the effective cost. If you picked that strike because you truly wanted QQQ at that price, assignment is just stage two of your plan. It becomes a problem only when you sold a put on something you didn’t actually want to own.

7 common cash-secured put mistakes

  1. Chasing high premium. Rich premium usually means the market expects larger moves.
  2. Picking a strike you can’t afford. Always calculate strike × 100 × contracts first.
  3. Treating premium as free money. It’s payment for an obligation.
  4. Ignoring opportunity cost. In a big rally, you may earn only the premium.
  5. Forgetting early assignment. It can happen before expiration.
  6. Selling puts on something you wouldn’t own. That breaks the logic of the strategy.
  7. Ignoring liquidity. Wide bid-ask spreads make getting in and out more expensive.

When should you NOT sell a cash-secured put?

  • You wouldn’t be comfortable owning the shares at the strike.
  • The cash commitment would be an uncomfortably large share of your account.
  • You need that cash in the near term.
  • You’re expecting a sharp drop and hoping to profit from it.
  • You’d panic-sell if assigned during a decline.

A beginner’s checklist before you sell

  1. Do I actually want to own this?
  2. Am I comfortable buying 100 shares per contract?
  3. Is the strike an acceptable purchase price?
  4. Have I worked out the breakeven?
  5. Have I calculated the total cash commitment?
  6. Do I understand the expiration?
  7. Have I checked implied volatility?
  8. Is the options chain liquid enough?
  9. Have I looked at trend, support and resistance?
  10. Can my account handle assignment?
  11. What’s my plan if the price falls sharply?
  12. What’s my plan if it rallies strongly?

If you can’t answer most of these, do more research before placing the trade.

Learn SPY and QQQ options with MySpyOptions

Understanding the mechanics is one thing. Applying them under real market pressure is another. MySpyOptions’ SPY and QQQ training covers strategy execution, SPY and QQQ tactics, risk management and live market sessions, so concepts like strike selection, implied volatility and position sizing connect to real setups. The goal is to understand why a trade makes sense rather than simply following an entry.

Summary

A cash-secured put means selling a put while holding enough cash to buy the underlying if assigned. It can offer premium income and a lower effective entry price, but it also brings assignment risk, real downside, capped upside and a big capital requirement. The one rule to remember: only sell a put at a strike where you’d genuinely be comfortable owning the shares.

Frequently asked questions

What is a cash-secured put in simple terms?

It’s selling a put option while keeping enough cash to buy the underlying if you’re assigned. You get a premium upfront. If the option expires worthless you keep it, and if assigned you buy at the strike.

Are cash-secured puts safe for beginners?

They’re easier to understand than many multi-leg strategies, but they aren’t risk-free. A big drop in the underlying can cause substantial losses, and you should be financially and psychologically ready to own the shares.

How much money do I need for a cash-secured put?

Generally the strike × 100 per contract. A $100 put needs about $10,000, though exact requirements depend on your broker.

Can you lose money with a cash-secured put?

Yes. If the underlying falls well below the strike, the premium only cushions part of the loss. The worst case is roughly (strike − premium) × 100.

What happens if a cash-secured put expires out of the money?

It expires worthless, you keep the premium, and the reserved cash is freed up, subject to your broker’s procedures.

Can a cash-secured put be assigned early?

Yes. Equity and ETF options can be assigned before expiration, and the risk is higher when the put is in the money.

Is a cash-secured put better than a limit order?

They do different jobs. A limit order pays nothing and carries no obligation. A cash-secured put pays a premium in exchange for a purchase obligation.

Can I sell cash-secured puts on SPY and QQQ?

Yes. Because a contract covers 100 shares, pay close attention to the cash required and your position size.

What’s the difference between a cash-secured put and a naked put?

Both are short puts, but a cash-secured put is fully backed by cash. A naked put isn’t, and it relies on margin with very different risks.

Categories
Finance Options Trading

Options Flow vs Alerts: Which Is Better?

Options flow vs alerts: which is better? Neither wins outright. Options flow is the raw stream of options trades, showing what traded. Options alerts are notifications that flag selected activity, showing what may deserve a look. Flow gives you depth; alerts save you time. Most SPY and QQQ traders do best using both.

  • Flow = the full tape of options trades. Alerts = a filtered nudge.
  • Alerts are better if your screen time is limited. Flow is better if you want to investigate.
  • A big trade isn’t a trading thesis. It could be a hedge, a spread or a closing trade.
  • Use an alert to notice, flow to investigate, and your risk rules to decide.

What is options flow?

Options flow is the live stream of individual options transactions in the market. Depending on your platform, each line might show the ticker, call or put, strike, expiration, contract size, premium, execution price and timestamp.

Think of it as the tape. It tells you what traded, and nothing about why.

Traders typically scan flow for large transactions, sweeps across exchanges, block trades, repeat activity in a single contract, and volume that’s high relative to open interest. That last one matters because volume and open interest measure different things: volume is what traded in a session, while open interest is what’s still outstanding.

A quick SPY example

Say you spot this: SPY, 1,500 calls, $1.2 million in premium. That works out to roughly $8.00 per contract (1,500 × 100 × $8.00). It looks like a strong bullish bet.

But the number alone can’t tell you:

  • whether the calls were bought or sold
  • whether the trade opened or closed a position
  • whether it was one leg of a spread
  • whether it was hedging a stock portfolio
  • what SPY and implied volatility were doing at that moment

Flow hands you the first piece of evidence. It doesn’t hand you the conclusion.

What are options alerts?

Options alerts are notifications triggered when a preset condition is met. That condition might be unusual volume, a large premium trade, a sweep or block, a VWAP cross, a jump in implied volatility, or a combination of technical and options-market signals.

So if flow is the tape, alerts are the tap on your shoulder. They’re built for people who can’t stare at a scrolling feed all day.

There’s one catch. An alert is not a trade signal. It says something happened. Whether that something fits your plan is still your call, and it matters more with options because leverage magnifies losses as well as gains, as FINRA points out.

Options flow vs alerts: the key differences

Factor Options flow Options alerts
Main job Show market activity Flag selected activity
Information volume High Lower
Filtering You or the platform Usually built in
Delivery Real-time or near real-time feed Push notification or message
Effort to interpret High Moderate to high
Best for Research and investigation Efficient monitoring
Biggest risk Information overload False confidence
Question it answers “What’s trading?” “What should I look at?”

The simplest way to see it: flow is the information layer and alerts are the attention layer. They aren’t really rivals. In practice, the workflow looks like this:

Market activity → Flow data → Filter → Alert → Validation → Decision

Which is better for SPY and QQQ traders?

It depends on your experience and how much time you can give the screen.

SPY tracks the S&P 500 and QQQ tracks the Nasdaq-100. Both have deep, liquid options markets, which is exactly why flow and alerts are so popular for them.

If you’re a beginner, alerts are easier to start with because there’s less to process. Just don’t treat one as an automatic entry. Work through it: understand the setup, check price action, look at the contract, size the risk, then decide.

If you’re intermediate, flow starts to earn its keep. Instead of reading “bullish SPY call alert” and stopping there, you can check the strike, expiration, premium, volume versus open interest, where it executed relative to the bid and ask, and how price sits against VWAP.

If you’re experienced, a detailed feed lets you build your own filters and blend flow with technicals, volatility and risk rules. That doesn’t make flow more accurate. It just gives you more raw material.

Quick decision guide

Your situation Start with
New to options Alerts plus education
Limited screen time Alerts
Want to dig into unusual trades Flow
Want full market visibility Flow
Trade only a few defined setups Filtered alerts
Want to understand why an alert fired Flow
Active intraday trader Flow plus alerts

The FLOW framework: a simple way to use both

We use a four-step routine so an alert never turns into a knee-jerk trade.

F: Find. Let flow or an alert surface the unusual activity. Filters help you avoid drowning in data.

L: Look at the context. Open the chart and the options chain. Check support and resistance, VWAP, moving averages, RSI, MACD, volume, implied volatility, strike, expiration and open interest.

O: Observe the structure. Does it look directional, or part of something bigger? Watch for multiple strikes or expirations, put and call combinations, repeated prints and possible hedges.

W: Weigh the risk. Before you click anything, write down your entry, maximum loss, position size, invalidation point, reward-to-risk and exit plan.

The framework isn’t there to replace your judgment. It’s there to make sure you actually use it.

Why alerts are still valuable

You can’t watch every options print across the U.S. market. Nobody can. A good alert system turns thousands of events into a handful worth your attention. That helps most when you trade only SPY and QQQ, have a day job, work from predefined setups, or already know how to validate a trade.

The danger is dependency. If you get ten bullish alerts and treat each as a recommendation, the filter has quietly taken over your decision-making.

6 common mistakes when using flow and alerts

  1. Assuming big premium means smart money. A large trade proves a large trade happened. It doesn’t prove the buyer was right, or even bullish.
  2. Treating every call as bullish. Calls can be sold, hedged or paired with other positions.
  3. Mixing up volume and open interest. They’re different metrics, so don’t swap one for the other.
  4. Ignoring bid-ask execution. Where a trade prints hints at urgency, but it doesn’t reveal intent. Wide spreads also raise slippage; the OIC explains bid and ask in its education resources.
  5. Chasing a stale alert. Twenty minutes is a long time in options. Price, volatility and structure may have already moved.
  6. Forgetting the Greeks. You can call SPY’s direction correctly and still lose money if your strike, expiry or timing was off. Delta, gamma, theta and vega all shape the outcome.

A 60-second checklist before acting on an alert

Ask yourself:

  1. What exactly triggered this alert?
  2. Is the activity unusual for this contract or underlying?
  3. What are the strike and expiration?
  4. What’s the current bid-ask spread?
  5. What do volume and open interest show?
  6. Could this be a spread or a hedge?
  7. Does SPY or QQQ price action confirm the idea?
  8. Where are VWAP and key support and resistance?
  9. What happens if I’m wrong?
  10. Does the size fit my risk limit?

If you can’t answer most of these, treat the alert as a research prompt, not an entry.

Build the process, not just the habit

Knowing the difference between flow and alerts is a start. Using either well takes a repeatable process. MySpyOptions’ SPY and QQQ options training covers options fundamentals, the Greeks, SPY and QQQ setups, risk management and live market sessions, and its alerts come with the reasoning behind them. The aim is to move from “what should I trade?” to “what’s happening, why does it matter, and does it fit my plan?”

Frequently asked questions

Is options flow better than options alerts?

Neither is universally better. Flow gives more detail, and alerts give efficiency. Traders who like deeper analysis may prefer flow, and traders who need fast monitoring may prefer alerts.

Are options flow alerts reliable?

An alert can accurately report that a trade or condition occurred. That doesn’t mean the trade will be profitable, because large trades can be directional bets, hedges, spreads or closing transactions.

Can you trade SPY options using options flow?

Yes, as one input. It works best alongside price action, volume, open interest, implied volatility, technical levels and a defined risk plan.

What’s the difference between options flow and unusual options activity?

Flow is the broad stream of transactions. Unusual options activity is a filtered subset that stands out by volume, premium, size or relative activity.

Should beginners use options flow?

They can study it, but they should first learn calls, puts, strikes, expirations, implied volatility, the Greeks and open interest. Flow only helps if you understand what you’re looking at.

Do large options trades mean institutions are buying?

Not necessarily. Public data generally doesn’t reveal who traded or why. A large print could come from an institution, a market maker, a retail trader or a multi-leg strategy.

Should I follow options alerts blindly?

No. Treat each alert as an event to review. Check the trend, contract, liquidity, volatility, catalyst and your risk limits before acting.

Categories
Finance Options Trading

How to Find High-Probability Trades Using Scanners

An options scanner can save you hours of digging through hundreds of contracts. But finding a setup and finding a good trade are two different things — and that gap is exactly where most scanner-based strategies fall apart. A solid options scanner strategy doesn’t stop at the alert. It uses the scanner to narrow the field, then applies a consistent process — liquidity, price action, implied volatility, technical confirmation, contract selection, and risk management — to decide whether what the scanner found is actually worth trading.

Quick answer: An options scanner strategy is a rules-based way of using a scanner to filter thousands of contracts down to a short list, then confirming each candidate against the underlying’s price action before you ever look at strike or expiration. The scanner’s job is to reduce how many decisions you have to make — not to make the trading decision for you.

What Is an Options Scanner Strategy?

At its core, an options scanner strategy is a rules-based process for identifying contracts or market conditions that match criteria you’ve already decided matter — volume, open interest, implied volatility, Delta, expiration, price, or unusual activity. Instead of hunting randomly through an options chain, you set the filters first and only investigate the candidates that actually clear them.

Think of the scanner as an idea-generation and filtering tool, not a decision-maker. It can surface a contract that looks great on paper and still be wrong for you — poor liquidity, inflated implied volatility, no technical confirmation, or a risk-to-reward ratio that doesn’t hold up once you look closer.

A practical version of the workflow looks like this: scan the market for potential setups, filter using liquidity and strategy-specific criteria, confirm the underlying with price action and technicals, select the right strike and expiration, define your risk, and only then execute — or reject — the setup based on your own rules. The goal isn’t to find the most active option on the board. It’s to find the option that satisfies your complete setup.

The Three Types of Options Scanners (And When Each One Fits)

Not every scanner is solving the same problem, so it’s worth being specific about what you actually want yours to find.

Criteria-based scanners search using predefined characteristics — Delta, Theta, Gamma, Vega, implied volatility, IV rank, open interest, volume, days to expiration, strike price. These are most useful once you already have a strategy. If you want SPY calls in a particular Delta range with a specific expiration, you don’t need an unusual-flow scanner — you need a criteria-based one.

Unusual activity and options-flow scanners flag large trades, sweeps, blocks, unusual volume, oversized estimated premium, and volume relative to open interest. They’re excellent for generating ideas and spotting where attention is building, but they won’t tell you whether a trade was opened, closed, hedged, or built as one leg of a spread.

Alert-based watchlist scanners monitor a limited group of symbols and notify you when specific conditions trigger. For an SPY and QQQ trader, this can be particularly efficient, since your universe is intentionally small — you’re watching two tickers, not two thousand. That lets you track things like price relative to VWAP, breakouts, volume expansion, options volume, IV shifts, and key support/resistance levels without drowning in noise.

The best scanner is the one that matches your process. A flow scanner is built for finding unusual activity; a criteria-based scanner earns its keep once you already know what characteristics your strategy needs.

Building a High-Probability Options Scan

“High probability” gets thrown around loosely, so it’s worth being precise: no scanner can guarantee a winning trade. What you can build is a setup where several independent conditions all point the same direction — which is a meaningfully different, more honest goal.

Step 1: Start with the underlying, not the option

Before you ever look at a contract, look at SPY or QQQ itself. Is the market trending or ranging? Is price above or below VWAP? Where do the major support and resistance levels sit? Is volume expanding, and is momentum strengthening or weakening? Is there a major economic event on the calendar? Skipping this step is how traders end up falling for an attractive-looking option in a market environment that doesn’t actually support the trade.

Step 2: Apply liquidity filters before anything else

Liquidity is one of the most important — and most commonly ignored — scanner filters. You want adequate options volume, adequate open interest, tight bid-ask spreads, and a contract you can realistically enter and exit. A theoretically great trade becomes a headache to manage if the spread eats your edge before you’re even filled. SPY and QQQ are generally more liquid than most individual-stock options, but that doesn’t mean every strike and expiration on the chain is equally efficient — some corners are still thin.

Step 3: Choose the expiration to match the thesis, not the premium

The wrong question is “which expiration makes this option cheapest?” The right one is “how much time does my thesis actually need to play out?” An intraday momentum idea usually wants same-day or very short-dated options; a short swing might need several days to a few weeks; a bigger directional thesis benefits from more time; premium-selling strategies often run longer than an intraday setup; and an event-driven trade should have its expiration chosen around the catalyst and volatility itself. Short-dated contracts react fast, but that speed comes with real sensitivity to time decay and shifting Delta and Gamma — worth remembering before you reach for the cheapest strike on the board.

From Scanner to Chart: The Confirmation Framework

One of the single biggest upgrades you can make to an options scanner strategy is simply separating discovery from confirmation. The scanner finds the candidate. The chart decides whether that candidate deserves your attention.

Bullish example: Say an SPY scanner flags increasing call volume, strong options liquidity, a concentrated expiration, and rising underlying volume. That’s not a green light to buy a call yet. First check whether SPY is holding above an important support level, trading above VWAP, forming higher highs and higher lows, showing expanding volume during the move, and has room before the next major resistance. If the options signal and the price structure agree, the setup earns a closer look. If SPY is failing resistance and losing VWAP at the same time the scanner lit up, that signal deserves a lot less weight than it first appeared to carry.

Bearish example: QQQ shows unusually high put activity. Before acting, check whether QQQ is below VWAP, whether support has actually broken, whether selling volume is increasing, whether momentum is weakening, and whether the move is showing up across the broader Nasdaq-100 rather than in isolation. You’re looking for confluence — multiple things agreeing — not a reason to confirm what you already wanted to believe.

SPY vs. QQQ: Why One Scanner Setting Doesn’t Fit Both

A single scanner configuration shouldn’t be applied blindly to every underlying you trade. SPY represents broad S&P 500 exposure; QQQ tracks the Nasdaq-100, and Nasdaq itself describes QQQ as one of the principal ETF vehicles providing exposure to that index — 100 of the largest non-financial companies listed on Nasdaq. That structural difference is exactly why QQQ often reacts differently than SPY when growth and technology sentiment shifts.

Factor SPY QQQ
Underlying S&P 500 Nasdaq-100
Market context Broad U.S. equity market Large-cap, technology-heavy growth exposure
Useful confirmation SPY trend, VWAP, breadth, macro levels QQQ momentum, technology leadership, Nasdaq levels
Important catalysts Fed, CPI, jobs data, broad macro news Rates, technology earnings, Nasdaq momentum
Scanner approach Emphasize market-wide conditions Weight momentum and technology-sector context more heavily

Using the Greeks to Choose the Right Contract

Once the scanner surfaces a candidate, the next question is whether that specific contract actually expresses your thesis efficiently. Delta approximates sensitivity to a move in the underlying; Gamma measures how quickly Delta itself changes; Theta measures sensitivity to time passing; Vega measures sensitivity to implied volatility. Don’t pick a contract just because it shows the highest potential percentage return — work backward instead, from market view, to desired exposure, to the volatility environment, to expiration, to Delta, to risk. An aggressive short-term trader might prefer more Gamma exposure; someone with a longer-duration thesis usually prioritizes extra time to expiration instead.

Implied volatility deserves its own pause here. IV represents the market’s expectation of future price variability, priced directly into the option. A scanner can hand you a contract with attractive directional characteristics that’s simply expensive because IV happens to be elevated right now — which raises a question worth asking every time: is the idea correct, but the option itself poorly priced for the current environment? That’s exactly why contract selection should happen after the underlying thesis is established, not before.

A 7-Point Scanner Checklist Before You Enter

Run through this before acting on anything a scanner flags:

  1. Market — What is SPY or QQQ actually doing right now? Trending, reversing, or ranging?
  2. Setup — What caused the scanner to flag this contract in the first place?
  3. Confirmation — Does price action agree with the signal?
  4. Contract — Is the strike and expiration appropriate for the thesis?
  5. Quality — Are liquidity, IV, and the Greeks acceptable?
  6. Risk — Where is the trade invalidated, and how much capital is on the line?
  7. Fit — Does this actually match your existing trading rules, or are you bending the rules to fit the alert?

If several of these come back unclear, the scan has still done its job — it found something worth investigating. That’s not the same as finding something worth trading.

Common Scanner Mistakes Worth Avoiding

Chasing the highest volume on the board is a natural instinct, but activity alone isn’t an edge — ask why the volume is elevated and whether the underlying actually confirms it. Piling on dozens of filters can backfire the other way, producing a clean-looking list with almost nothing usable in it; start with the handful of variables that genuinely matter to your strategy and resist the urge to add more.

Bid-ask spreads get ignored more often than they should. A contract can show impressive volume and still carry an inefficient spread that quietly eats your edge — always check the actual quote before entering, not just the headline volume number. Scanner “scores” are another trap: a number is only as good as the methodology behind it, and a score without a visible methodology shouldn’t replace your own judgment.

Cheap out-of-the-money options look tempting precisely because they’re cheap, but low premium doesn’t mean good value — an inexpensive option can carry a genuinely low probability of finishing profitable, especially if the underlying needs a large move before expiration. Time decay compounds this: a trade can be directionally right and still lose money if the underlying doesn’t move fast enough, and that pressure only intensifies as expiration nears. And perhaps the most common mistake of all is letting the scanner override the plan — the scanner should fit your strategy, not the other way around. Your rules shouldn’t change every time a new alert fires.

A Repeatable Daily Workflow for SPY and QQQ Traders

Before the open: review the economic calendar, any major overnight moves, current SPY and QQQ levels, the previous day’s high and low, key support and resistance, expected volatility, and any scheduled catalysts.

During the session: run your scanner for volume expansion, unusual options activity, liquidity, technical breakouts, VWAP conditions, IV changes, and relevant Delta ranges.

Before entry: move from the scanner to the chart and ask whether the underlying confirms the options signal. If yes, examine the contract itself. If no, wait — there’s no rule that says every alert needs a trade attached to it.

After entry: define your stop-loss or technical invalidation level, profit target, maximum acceptable loss, position size, exit conditions, and maximum holding period.

Strung together, that’s a complete process — not a pile of disconnected indicators you’re reacting to one at a time.

Learn Scanner-Based SPY and QQQ Trading with MySpyOptions

A scanner is easiest to use well when it’s treated as one piece of a broader trading system rather than the whole system. MySpyOptions focuses specifically on SPY and QQQ options, combining market analysis, technical concepts, options-strategy education, and live-market learning — with an emphasis on practical trade selection, risk management, strike and expiration selection, and reading price action, rather than leaning on alerts alone.

That distinction tends to matter most for newer traders. A scanner can show you what happened. Working through the reasoning with experienced traders helps you understand why a setup matters, when it’s invalid, and how the option should actually be structured around the thesis — which also tends to reduce the temptation to rewrite your scanner settings or trading rules after every losing trade.

For traders focused specifically on SPY and QQQ, MySpyOptions’ approach is built around SPY- and QQQ-specific market analysis, practical options strategies, live-market examples, technical analysis, contract and expiration selection, position sizing and risk management, and ongoing trader support and mentorship. The goal was never to make you dependent on a scanner or an alert service — it’s to help you learn how to evaluate the setup yourself.

What Actually Makes a Scanner-Based Trade High-Probability?

A scanner can’t make a trade high-probability on its own. A more honest definition: a high-quality scanner setup is one where several independent factors point to the same thesis, and the potential reward justifies the defined risk. Picture it as a chain — scanner signal, then market context, then technical confirmation, then contract selection, then risk control. As an example: QQQ call activity shows up → the broader Nasdaq environment is bullish → QQQ is holding above VWAP → a breakout confirms it → you select a suitable Delta and expiration → you set a predefined stop before entering.

Each link in that chain is handling a different type of uncertainty. The scanner handles discovery. Technical analysis handles timing and market structure. The Greeks and IV help with contract selection. Position sizing handles risk. Put together, that’s the actual purpose of an options scanner strategy — not finding the loudest alert on the screen, but building a repeatable filter for genuinely well-supported setups.

Frequently Asked Questions

What is an options scanner strategy?

An options scanner strategy is a rules-based process for using a scanner to find contracts that match predefined conditions — volume, open interest, implied volatility, Delta, expiration, or unusual activity. Traders then confirm the setup against the underlying’s price action and apply predefined risk-management rules before entering.

How do I find high-probability options trades with a scanner?

Start by defining your strategy and scanning only for conditions that support it. Filter for liquidity, volume, open interest, expiration, and relevant Greeks, then confirm the underlying with price action, VWAP, support and resistance, and volume. Select the contract and define your maximum risk before entering.

What should I scan for when trading SPY and QQQ options?

Volume expansion, unusual options activity, liquidity, implied volatility, Delta, expiration, and technical conditions. Since SPY and QQQ have different underlying exposures, it also helps to weigh broad-market conditions for SPY and Nasdaq-100 or technology-sector momentum for QQQ.

Can an options scanner predict winning trades?

No. A scanner identifies contracts or conditions that meet specific criteria, but options prices are affected by the underlying’s movement, time, implied volatility, and other factors a scanner can’t forecast. It should be used as a filtering and idea-generation tool, not a prediction system.

What is the best way to use an options scanner?

Treat it as the first step in a repeatable process: scan, filter, confirm, select, manage risk. Start with the underlying market, use the scanner to narrow candidates, confirm the setup with technical analysis, choose an appropriate contract, and define the invalidation point before entry.


Categories
Finance Options Trading

How to Use Unusual Options Activity for Better Trades

If you trade options on SPY or QQQ, you’ve probably seen a flow alert flash across your screen — a block of calls three times the average volume, or a sweep that looks too aggressive to ignore. The instinct is to treat it as a tip. It isn’t one.

Unusual options activity (UOA) is a genuinely useful signal, but it’s a research signal, not a trade signal. A large call or put print doesn’t tell you whether a trader is bullish or bearish, and it certainly doesn’t guarantee where price goes next. The real edge comes from combining that flow with the options chain, price action, implied volatility, and a few technical levels — then deciding whether the setup is actually worth the risk.

Quick answer: Unusual options activity flags where attention is building in the options market. It doesn’t tell you why it’s building or whether the trade will work. Treat it as a starting point for research, confirm it against price action, and only then build a risk-defined trade around it.

What Counts as “Unusual,” Exactly?

There’s no exchange-mandated threshold for unusual options activity — no regulator hands out a rulebook that says “5,000 contracts = noteworthy.” Scanners build their own definitions using volume relative to open interest, historical volume, premium size, and how aggressively the order was executed.

That’s why context matters more than the raw number. A 5,000-contract trade can be extraordinary in one name and routine in another. A few quick comparisons:

  • High volume paired with low historical activity → worth a second look
  • High volume in an already hyper-liquid SPY strike → often just noise
  • A large call trade against a falling underlying → needs investigating before you assume anything bullish
  • A large put trade during a rally → could easily be a hedge, not a bearish bet
  • High volume with unchanged open interest → not proof anyone opened a new position

Volume vs. open interest, briefly: volume is contracts traded today. Open interest is contracts still outstanding after the prior session’s clearing. High volume relative to OI tells you a contract is unusually active — it does not tell you that every one of those contracts represents a fresh directional bet. Confusing the two is probably the single most common mistake in flow analysis.

A Four-Step Framework: Signal → Context → Confirmation → Risk

1. Signal — what actually looks unusual?

Start with the raw mechanics: contract volume, the volume/OI relationship, estimated premium, strike, expiration, whether it printed as a sweep or a block, and where it executed relative to the bid/ask. One large print is interesting. Several related prints — same strike, similar timing, growing size — are more informative, because they hint at concentration and persistence rather than a single one-off order.

2. Context — why might this trade exist?

Before you assign a direction to anything, check what’s actually happening around it: the economic calendar, upcoming earnings, Fed announcements, CPI or jobs data, sector strength, and where SPY or QQQ sit relative to known support and resistance. Skipping this step is how traders end up reading a hedge as a bearish bet, or a rolled position as a brand-new one.

3. Confirmation — does price agree with the flow?

Say you spot heavy call buying in QQQ. On its own, that’s not a trade. Ask whether QQQ is actually holding above VWAP, whether it’s printing higher highs on expanding volume, whether RSI is confirming momentum rather than flashing exhaustion, and whether MACD supports the move. The same logic runs in reverse for puts. Flow without price confirmation is a lead, not a thesis.

4. Risk — where does the idea get proven wrong?

Before you enter anything, define your maximum dollar risk, position size, entry, stop-loss or technical invalidation level, profit target, and a time limit. This is the step that turns an interesting alert into an actual trading plan instead of a hunch with a ticker attached.

The Five UOA Signals Worth Watching Most

  1. Volume relative to open interest. A contract trading several multiples of its displayed open interest deserves a closer look — but a high volume/OI ratio alone doesn’t prove new buying. It could just as easily be closing activity, a roll, or one leg of a spread.
Metric Observation
Open interest 2,000
Session volume 12,000
Volume/OI 6×
Expiration 14 days
Strike Slightly OTM

That’s a real spike. It still doesn’t tell you whether it’s buying, selling, or something structural like a roll.

  1. Sweep orders. A sweep — an order routed aggressively across multiple exchanges to grab available liquidity — is a genuine urgency signal. It’s a timing clue, not proof that the trader behind it knows something you don’t.
  2. Block trades. A large block at the ask can look bullish on the surface, but it might be a hedge, one leg of a spread, a closing trade, a roll, or a fresh directional bet. “Block” and “institutional bullish conviction” are not the same thing, however often they get treated that way.
  3. Premium concentration. Estimated premium tells you where dollars are concentrated — it’s not the same as confirmed directional capital. A large headline premium can just as easily come from high volume, an expensive option, or both.
  4. Expiration and strike concentration. When activity clusters around one expiration and a handful of nearby strikes, it often signals a time-sensitive thesis. For SPY, that usually means watching macro catalysts and broad index levels. For QQQ, technology-sector leadership and mega-cap earnings tend to matter more.

SPY vs. QQQ: Why the Same Signal Means Different Things

SPY tracks the S&P 500 — broad, large-cap, heavily influenced by macro and rate expectations. QQQ tracks the Nasdaq-100 — more concentrated, more tech-and-growth-driven, and typically more reactive to individual mega-cap earnings.

Factor SPY Options QQQ Options
Underlying exposure Broad U.S. large-cap market Nasdaq-100
Main context Macro, rates, CPI, Fed policy Tech leadership, growth, mega-cap earnings
Useful confirmation Trend, VWAP, breadth, major levels Momentum, tech leadership, major levels
Typical UOA interpretation Often tied to hedging or index positioning Reacts sharply to sector catalysts
Key risk Macro reversals, volatility shifts Fast momentum reversals

Unusual put activity in SPY is frequently portfolio hedging rather than a directional bet. A large QQQ position built around a known tech catalyst usually has a more obvious event-driven explanation. Either way, the lesson is the same: calls and puts don’t carry a fixed meaning. Context decides that.

A Repeatable Process You Can Run Every Session

Step 1 — Start with the underlying, not the flow. Look at SPY or QQQ first: trend, support/resistance, VWAP, moving averages, volume, RSI, MACD, and any major catalyst on the calendar.

Step 2 — Find what’s actually unusual. Filter for volume, volume/OI, premium size, sweeps, blocks, repeated prints, and strike or expiration concentration.

Step 3 — Ask if the flow has a plausible explanation. Directional speculation, hedging, earnings positioning, volatility trading, spread construction, a roll, or simple profit-taking can all produce the same-looking print. If you can’t land on a reasonable explanation, don’t force one.

Step 4 — Check the flow against price.

UOA Price Action Interpretation
Bullish-looking calls Bullish breakout Stronger confirmation
Bullish-looking calls Price below resistance Wait for confirmation
Heavy puts Bearish breakdown Stronger confirmation
Heavy puts Price rising Investigate possible hedge
Calls and puts both elevated Choppy market Possibly volatility/spread activity
Huge volume, no price response — No confirmation — treat cautiously

Step 5 — Build the trade around risk, not around the flow print itself. You don’t need to copy the exact contract that showed up on the scanner. A different strike, expiration, or a defined-risk spread may fit your actual thesis better — and your risk-to-reward should be decided before you’re in the trade, not after.

Mistakes That Quietly Wreck a UOA-Based Process

It’s easy to assume every call is bullish, but calls get sold, hedged, and folded into spreads constantly. The reverse mistake is just as common: a fund holding a large equity position will often buy puts purely for protection, not because it’s turned bearish.

Volume and open interest also get conflated more than they should. They’re different measurements, and high volume alone doesn’t tell you who opened or closed a position. There’s also a timing trap — by the time a large trade becomes visible on a scanner, its premium may have already moved meaningfully, so chasing the exact contract often means chasing a worse price than the original trader got.

Implied volatility is another blind spot. Even if the underlying moves the way you expected, falling IV can still erode the option’s value and eat into — or erase — the gain. And oversized position sizing turns leverage from a tool into a liability: the SEC has been explicit that option buyers can lose their entire premium, and some option-writing strategies carry risk well beyond that. The most important reminder ties all of this together — unusual doesn’t mean correct. UOA tells you something unusual happened. It says nothing about whether the trader behind it will be proven right.

The 10-Point UOA Checklist

Before acting on any unusual options activity alert, run through this:

  1. Is the underlying trending?
  2. Is the activity genuinely unusual for that specific contract?
  3. How large is volume relative to open interest?
  4. Is the activity concentrated in one strike or expiration?
  5. Does the execution suggest urgency (sweep vs. routine order)?
  6. Could this be a hedge or part of a spread?
  7. Is there a known catalyst behind it?
  8. Does price action confirm the apparent direction?
  9. Is implied volatility reasonable for this setup?
  10. Where does the trade get invalidated, and how much are you willing to lose?

If more than a couple of these come back unclear, waiting is usually the better trade than forcing one.

Learn SPY and QQQ Options Trading with MySpyOptions

Reading options flow gets a lot easier once you actually understand the underlying market first — which is a big part of why structured education matters here. At MySpyOptions, the focus is specifically SPY and QQQ options: market structure, options chains, technical analysis, trade planning, and risk management, taught in live market conditions rather than through static, theoretical examples.

That distinction matters. Traders who learn to build and stress-test a live setup, rather than just receive an entry and exit, tend to develop judgment that holds up when the market doesn’t behave the way the textbook example did. What sets the approach apart:

  • SPY and QQQ specialization instead of a generic options curriculum
  • Practical education built around real trading conditions
  • Structured risk management and defined trade planning
  • Options-chain and price-action concepts that complement flow analysis
  • Trader support and mentorship for interpreting live setups as they happen

The goal isn’t to hand traders a signal to follow — it’s independence: understand the setup, weigh the evidence, manage the risk, and make the call yourself.

FAQs

What is unusual options activity?

Unusual options activity is trading that stands out from a contract’s normal behavior — through unusually high volume, an elevated volume-to-open-interest ratio, large premiums, sweep orders, block trades, or concentration around specific strikes and expirations. It flags contracts worth investigating; it doesn’t predict where price goes next.

How do you identify unusual options activity?

Look for volume that’s unusually high relative to open interest or the contract’s typical activity, along with large premiums, repeated sweeps, block trades, aggressive executions, or unusual concentration at certain strikes or expirations. Always weigh those signals against the underlying’s current price action and broader market conditions.

Is unusual options activity bullish or bearish?

It can be either, or neutral, depending on the trade. Heavy call activity can look bullish and heavy put activity can look bearish, but both can just as easily be sold, hedged, rolled, or built into spreads — which is why direction shouldn’t be assumed from calls or puts alone.

Can unusual options activity be used for SPY and QQQ trading?

Yes. It can help identify contracts, strikes, and expirations attracting extra attention. For SPY, weigh broad-market and macro conditions; for QQQ, Nasdaq-100 momentum and tech-sector catalysts add useful context. UOA is most useful when it confirms what price is already showing.

Is unusual options activity a reliable standalone trading signal?

It’s better treated as a research and confirmation tool than a standalone signal. A large trade can represent speculation, hedging, a roll, or spread construction. Pair UOA with price action, technical levels, implied volatility, known catalysts, and a defined risk plan before entering anything.


Categories
Finance Options Trading

Cash Secured Puts Explained for Beginners: How They Work, Benefits, and Risks!

A cash-secured put is an options strategy that may assist investors in earning income from option premiums while seeking to buy the underlying stock at a preferred price. In this strategy, rather than buying the stock immediately, an investor writes put options and keeps some cash available for buying the shares in case of exercise of those options. This strategy may be beneficial for the investor when they are neutral to slightly bullish on a stock and are ready to own the stock at the chosen strike price. 

However, the premium received from writing puts doesn’t cover the downside risk if there is a drastic fall in the underlying stock. In this article, we’ll learn about the basics of cash secured puts and their profits and losses, their application, and risks for beginners. Read on for a detailed analysis!

What are Cash Secured Puts?

A cash-secured put is the sale of a put option accompanied by the maintenance of the required amount of cash in the broker’s account for the purchase of the underlying shares in case the option is assigned. The premium is earned in return for the acceptance of the obligation to buy the stock at the previously agreed strike price.

The typical size of the standard equity options contract is equal to 100 shares, even though the details of the contract may differ across the markets and underlyings. So, in case the investor sells a put with a $50 strike price, then the necessary cash for 100 shares will be $5,000. The received premium will lower the cost of the purchase of the stock.

The term “cash-secured” stands for the money set aside for the potential purchase of the stock. Unlike a naked put, a cash-secured put is backed by sufficient cash rather than relying on margin to meet the potential purchase obligation.

How Do Cash Secured Puts Work?

The process starts with choosing a stock that the investor would want to buy. The investor does not buy this stock at the prevailing market price but sells a put option at a chosen strike price that represents their desired entry price.

There are two outcomes in this situation:

  • The stock is above the strike price: The put may expire without value, therefore allowing the investor to receive the whole premium without owning any stock.
  • The stock is below the strike price: The put will be assigned, and the investor will be obligated to purchase the stock at the strike price as per the conditions of the contract.

The premium provides partial protection against the fall of the price. The cost basis after the assignment is usually estimated as follows:

Effective Cost Basis = Strike Price – Premium Received

So, in the case of the sale of a $50 put with the $2 premium, the cost basis is equal to $48 per share.

Cash-Secured Put Example

Assume that the stock is trading at $85, and an investor wishes to buy the stock at $80. The investor sells one put contract with an $80 strike and gets a premium of $2 per share, or $200 in total for 100 shares.

The investor will keep $8,000 as cash for buying the shares if they fall below $80.

In case the stock is at $82 at expiration, then the put would remain out of the money and would expire without any value. The investor keeps the premium of $200 and doesn’t buy any shares.

If the stock falls to $70, the put will be assigned and the investor can buy 100 shares at the $80 strike price. After accounting for the $200 premium, the effective cost basis will be $78 per share. This shows that the cost basis remains $78 even when the stock falls significantly below the strike price.

This worked cash secured put example shows that the premium lowers the effective purchase cost but does not protect the investor from losses if the stock continues to decline.

Maximum Profit and Break-Even Price

The maximum profit for cash secured puts is equal to the premium received.

Maximum Profit = Premium Received × Number of Shares

For one contract with a premium of $2, the maximum profit is $200.

The break-even price is:

Break-Even Price = Strike Price − Premium Received

With an $80 strike price and $2 premium, the break-even price is $78. Above $78, the position can be profitable at expiration, while below $78, the position results in a loss if the put is assigned. If the stock remains above the $80 strike price, the put may expire worthless and the investor keeps the full $200 premium.

But here the risk is that if the stock price goes to zero, the maximum loss, which is calculated as Maximum Loss = (Strike Price − Premium) × Number of Shares, will be ($80 − $2) × 100 = $7,800, not including the transaction cost.

The following summary shows the key figures from the $80 strike and $2 premium example:

Strike Price Premium Cash Required Break-Even Max Profit Max Loss
$80 $2/share ($200 total) $8,000 $78 $200 $7,800

A cash secured put calculator can use these same inputs to estimate the cash requirement, break-even price, maximum profit, and maximum potential loss for a trade.

Why Do Investors Use Cash-Secured Puts?

One of the reasons investors use cash secured puts is because of the possibility of premium income with the desired entry price for the stock. Rather than just placing a limit order and waiting for execution, the investor gets premium income in return for taking on the obligation of buying the shares at the selected strike price.

The strategy can serve several objectives:

  • To get premium income: The seller receives the premium for opening the position.
  • To target a lower price for entry: The investor selects a strike price below the stock’s current market price. 
  • To reduce the effective entry cost: If the put is assigned, the premium received lowers the net cost of acquiring the shares. 
  • To put cash to good use: The capital kept aside for future stock purchase generates option premium while the position remains open.
  • To maintain a neutral to moderately bullish outlook: The seller expects the stock to remain at or above the strike price through expiration.

How to Trade Cash-Secured Puts

Trading cash secured puts involves selecting the stock, strike price, expiry, and premium and keeping sufficient cash for the assignment of shares. The following are the key steps to trade cash-secured puts:

1. Choose the Underlying Stock

Choose the stock that you have studied and are comfortable trading with even if the market goes against you. Quality, valuation, liquidity, and implied volatility may affect the choice of the stock.

2. Choose the Strike Price

The strike price should reflect how much you are willing to buy the stock at. Out-of-the-money puts are used mostly in such cases.

3. Sell Put to Open

Sell the put option while having enough cash to cover your assignment obligation. The premium is credited to the account by the broker.

4. Managing or Exiting Position

If the stock stays above the strike price, the option can expire without any action. You can also buy the put option to close your position before the expiration date. If the option is assigned, the investor purchases the shares at the strike price and then manages the resulting stock position

Some traders choose to close or adjust their positions before the expiration date after capturing most of the available premium, however, the actual approach may vary based on your trade and risk management strategy.

Risks Associated with Cash-Secured Puts

Though the reserve of cash adds some structure to the trade, cash secured puts are not risk-free trades. Here are some possible risks of this strategy:

  • Stock decline: The investor can receive stocks after the assignment, which will be worth much less than the strike price.
  • Limited profit: The maximum profit is limited to the premium, and the stock increase does not add any extra profit.
  • Capital lockup: Money needed for the potential assignment can’t be freely used to enter new positions until you close or change the existing one.
  • Opportunity loss: In case of a significant stock increase without reaching the strike, the investor earns the premium but misses the opportunity to get the shares at a lower price.
  • Fundamental deterioration: A stock that looked attractive when the put was sold may later face weaker earnings, business problems, or changing market conditions.

Conclusion

Cash secured puts can offer a way to collect premiums and target the desired price for buying stocks. However, this strategy works well only for those who have enough cash and are ready to own the underlying stock in case of its price fall. The collected premium can reduce the effective cost, but the strategy can still result in significant losses because of falling prices. 

To turn options concepts into practical market understanding, explore MySPYOptions for actionable education, market perspectives, and trading insights that can support more informed options decisions.

FAQs

1. What are cash secured puts?

Cash-secured puts are the strategy of selling a put option while having enough cash to buy the stock if there is an assignment and the investor wants to get the stock at the desired price.

2. How much money is needed for cash-secured puts?

Generally, the cash needed for the put is equal to the amount of money for purchasing the stock at the strike price, usually 100 shares for one equity option contract, so the premium for the strike price of $50 will be around $5,000.

3. What is the maximum profit from cash-secured puts?

The maximum profit from cash secured puts is limited by the premium received when the option was sold and is earned if the option expires without assignment or if the investor closes the position and makes money before then.

4. What happens if the cash-secured put expires in the money?

The investor receives an assignment of the put option and buys the shares at the strike price using the money reserved for the assignment.

5. Are cash-secured puts risky?

Yes, cash secured puts can involve substantial losses if the underlying stock declines significantly below the strike price, although the premium received provides a limited cushion by reducing the effective cost of the shares.


Categories
Options Trading

Rho Options Explained: The Most Ignored Options Greek

When considering options, investors analyze Greeks such as Delta, Gamma, Theta, and Vega. However, there is another Greek that can have a strong impact on the price of the option depending on interest rate changes: Rho.

Rho shows how sensitive the price of an option is to changes in the risk-free interest rate. Its effect becomes visible when time to expiration is large. Thus, knowing Rho allows assessing the position better under changed monetary conditions. In this article, we will look into Rho options, how Rho works, and why it is important for various options strategies.

What is Rho?

Rho is the measure that shows how much the theoretical price of an option may change in case of a 1% change in the risk-free interest rate. It isolates the effect of interest rates while assuming other pricing factors remain unchanged.

For example, if the Rho of an option is 0.30, its price will theoretically increase by $0.30 per share in case of a 1% increase in the risk-free interest rate and will fall by this amount in case of a 1% decrease.

The risk-free rate usually refers to government securities and, specifically, to Treasury rates in the United States. Traders can also take into account the interest-rate situation in the country when assessing longer-term positions.

Rho is often ignored since interest rate changes usually influence the price of an option less than changes in the price of the underlying asset or in the implied volatility. However, this does not mean that it is not important.

Why is Rho Called the Most Overlooked Options Greek?

The reason Rho is usually ignored is that many retail options trades have short expiration dates. Weekly and short-dated options have low interest rate exposure.

Meanwhile, longer-dated options have more exposure to the effects of financing and discounting, as the process takes more time. Therefore, even a minor change in the interest rate may become more important in the long term.

That is why Rho options are important when:

  •       Interest rates change fast
  •       Monetary policy of the Central Bank changes
  •       Traders hold long-dated options
  •       The positions are based on substantial capital
  •       Investors trade with the help of LEAPS and other long-term options
  •       Interest-rate expectations have a great influence on market sentiment

It is important to keep in mind that Rho is not always equally important in every trade. Its importance largely depends on the expiration, type of option, moneyness, and the rate situation.

How Does Rho Affect Calls and Puts?

There is an important difference between the Rho of calls and the Rho of puts. Call options usually have positive Rho. When interest rates increase, the theoretical value of a long call will grow if other factors remain the same. The increased rates decrease the present value of the strike price to be paid in the future.

Meanwhile, put options usually have negative Rho. When interest rates increase, the theoretical value of a long put will decrease. The opposite effect will occur in the case of decreasing rates.

For example, a call with a Rho of 0.25 could theoretically gain $0.25 per share from a 1 percentage-point increase in the relevant interest rate. A put with a Rho of -0.25 could theoretically lose $0.25 per share under the same assumption. These figures show the sensitivity but not guaranteed changes in the market price.

The Effect of Time to Expiration on Rho

Time to expiration is one of the main factors that determine Rho sensitivity. An option with expiration in several days has not much time left for interest-rate changes to have an influence on it.

Meanwhile, options with expiration in several months or in years have much more time for the influence. That is why longer-dated options usually have greater Rho. This effect is particularly important for LEAPS.

Traders who hold long-term calls or puts cannot ignore Rho because it may mean ignoring some part of the interest-rate exposure of the position. While under stable interest-rate conditions the effect may be modest, it can become much more important in case of monetary policy changes.

How Does Moneyness Influence Rho?

Rho options also vary according to an option’s moneyness. The relationship between moneyness and Rho can help explain how interest rates affect options differently, as discussed below.

In-the-money options

ITM options usually have greater Rho sensitivity than OTM options. Their intrinsic value and increased probability of exercising can make interest rate changes more important.

So, a deeply in-the-money call can react more strongly to changes in interest rates than a comparable out-of-the-money call.

At-the-money options

ATM options usually lie between ITM and OTM options regarding Rho sensitivity. Pricing of ATM options includes both intrinsic and time value, among other factors such as volatility.

Rho remains important, especially for options with longer expiries.

Out-of-the-money options

OTM options usually have lower Rho sensitivity. They depend heavily on time to expiration and volatility rather than on intrinsic value.

Nevertheless, even low sensitivity does not equal zero sensitivity. Large positions and longer expirations can make the effect worth monitoring.

A Simple Rho Options Example

Suppose a call option is priced at $10 with the relevant risk-free interest rate of 5%.

Suppose the rate rises to 6%, while other pricing variables remain unchanged. If the theoretical value increases to $10.50, then the price moves by $0.50 per share for a 1 percentage-point change in the interest rate.

Hence:

  • Rho (per share) = Change in option value ÷ Change in interest rate
  • Rho (per share) = $0.50 ÷ 1 percentage point = $0.50 per 1% rate change

With a standard 100-share contract multiplier, that translates to $0.50 × 100 = $50 in theoretical dollar value per contract, for each 1 percentage-point move in interest rates.

This example ignores the complex process of actual pricing. Actual prices are influenced not only by the risk-free interest rate but also by other factors, such as the price of the underlying asset, volatility, time decay, dividends, liquidity, and other factors.

How to Calculate Rho

Rho is a partial sensitivity of an option’s value to the risk-free interest rate. It is represented as follows:

ρ = ∂V / ∂r

Where:

  •       V is the option’s value
  •       r is the interest rate
  •       ρ is the sensitivity of option value to the interest rate

There are more complicated equations used in professional pricing models. According to the Black-Scholes model, Rho depends on factors such as strike price, time to expiration, volatility, and the ratio between the price of the underlying asset and the strike.

Usually, traders do not calculate Rho options themselves, options trading and analytics software provides this measure.

How Can Rho Be Used for Trading in Options Strategies?

Rho can be of significant help in the context of a whole risk-assessment system, but not in isolation. Below are some practical ways traders can use Rho across different options strategies.

  1. Assessment of Long-Dated Positions

If the trader holds a long-dated call or put, they can monitor Rho together with Delta, Vega, and Theta, giving a full picture of the position’s sensitivities.

  1. Assess Interest-Rate Scenarios

When monetary policy is expected to change, Rho helps estimate the direction of possible interest-rate exposure of the option.

In the case of positive Rho, the long call benefits from an interest-rate increase, while the opposite happens with the long put.

  1. Comparison of Different Expirations

When comparing two options with otherwise equal factors, Rho shows how much additional interest-rate exposure comes from choosing a longer expiration.

This approach is particularly useful when deciding between short-term and long-term options.

  1. Construction of Portfolio Hedges

Portfolio managers can consider Rho while building hedges using long-term options. Factoring in Rho can help surface exposures that other Greeks don’t capture.

  1. Combining Rho with Other Greeks

Each Greek considers a different aspect of an option’s risk.

Delta shows sensitivity to changes in the price of the underlying asset; Gamma shows changes in Delta; Theta shows the effect of time decay; Vega shows sensitivity to changes in implied volatility; and Rho shows interest-rate sensitivity.

When Should Traders Pay More Attention to Rho?

While long expiration and changing interest rates usually make Rho more important, traders should also take into account expiration, position size, and other market factors. The following situations can make Rho more relevant:

  •   Long-dated options can have greater sensitivity to interest-rate changes.
  •       Changing interest rates can increase the practical importance of Rho.
  •       Major central bank decisions may affect options with higher Rho exposure.
  •       Large positions can make small Rho changes more financially significant.
  •       LEAPS and other long-term strategies may require closer attention to Rho.
  •       Interest-rate-sensitive assets can make Rho more relevant to a trading strategy.
  •       Portfolio risk management can benefit from understanding overall Rho exposure.
  •       Short-term options may require less attention to Rho when rates remain stable.

Therefore, traders should focus on situations where interest-rate exposure could materially affect the position.

Rho vs Other Options Greeks

The table below compares the primary sensitivity of each Greek and the situations in which it becomes more relevant.

Greek Primary Sensitivity Generally More Relevant When
Delta Underlying price The underlying moves
Gamma Change in Delta Positions approach expiration
Theta Time decay Time passes
Vega Implied volatility Volatility changes
Rho Interest rates Rates and longer expirations matter


This comparison shows why Rho can remain hidden in short-term trading. Other Greeks often create larger day-to-day price effects. Still, Rho completes the broader picture of option-price sensitivity.

Conclusion

Although Rho is not as popular as other Greeks, it can reveal important interest-rate exposure. Its importance increases with long-dated options and changing monetary conditions. Knowing Rho options can help traders evaluate risks that may go unnoticed without considering Delta, Theta, Gamma, and Vega.

For actionable options education, market perspectives, and trading insights, visit MySPYOptions to strengthen your options knowledge and decision-making.

FAQs

  1. What does Rho mean in options trading?

Rho is the measure that shows how much the theoretical price of an option may change for a 1% change in the risk-free interest rate.

  1. Is Rho positive for call options?

Yes, call options generally have positive Rho, meaning the theoretical price of a call tends to increase as interest rates rise.

  1. Which options are most affected by Rho?

Long-dated options, particularly ITM contracts, generally show greater Rho sensitivity than short-dated or OTM options.

  1. Should traders use Rho alone when making decisions?

No, Rho should be considered alongside Delta, Gamma, Theta, Vega, expiration, moneyness, and broader market conditions.


Categories
Finance Options Trading

Vega Options Explained: Meaning, Formula, and Trading Impact

Vega options measure how sensitive an option’s premium is to shifts in implied volatility. An option’s price can change even when the underlying asset barely moves. The main driver behind that kind of move is implied volatility, the market’s forward-looking estimate of how much an asset’s price could swing. Vega is used to calculate how sensitive the option price is to a change in volatility. Understanding vega options helps traders weigh volatility risk before opening a position, rather than after. 

In this article, we will explain what vega options are, their formula, practical applications, and common trading mistakes to avoid. Read on for a detailed analysis!

What is Vega in Options?

Vega is an option Greek that measures the sensitivity of an option premium to the change in implied volatility. In simple terms: Vega tells you how much an option’s price is expected to move for every 1 percentage-point change in implied volatility, all else held equal. 

If Vega equals $0.60, this means that the option premium is expected to grow (decline) by approximately $0.60 if the implied volatility grew (declined) by 1 percentage point. Vega is applicable to both calls and puts, though its effect depends on the type of position opened. Vega is usually higher for at-the-money options and longer-dated options.

How Does Vega Impact Option Prices?

Implied volatility directly impacts the extrinsic value of an option. When there is an expected increase in volatility, premiums are likely to rise, while a decrease in volatility may lower premiums.

Long call and put options usually have positive Vega, meaning increased volatility is beneficial for them. Short options, on the other hand, normally have negative Vega, meaning they react negatively to increased volatility. Longer-dated options are more sensitive to volatility shifts than shorter-dated ones.

Vega does not measure volatility itself; it measures sensitivity to it.

Vega Options Formula (How to Calculate Vega)

The standard Black-Scholes model offers a mathematical approach to calculating Vega. The formula is:

Vega = S × φ(d₁) × √T

Where:

  •       S is the price of the underlying asset
  •       φ(d₁) is the standard normal probability density function at the point d₁
  •       T is the time remaining until the option’s maturity, in years
  •       d₁ is a function of the underlying asset price, strike price, volatility, interest rate, and time to expiration

This equation estimates the impact of implied volatility changes on an option’s theoretical value. Since market quotes are given in percentages, traders typically interpret Vega relative to a 1% change in implied volatility.

The precise calculation depends on the pricing model and contract specifications, so traders generally rely on the Vega figure provided by their trading platform rather than calculating it manually for every position.

Vega Options Example

An example helps clarify the concept. Assume a call option costs $12, with implied volatility of 20% and a Vega of $0.80.

If implied volatility rises from 20% to 21%, the estimated premium change would be:

$0.80 × 1 = $0.80

In this case, the option premium would move from $12 to $12.80, assuming all other factors stay constant.

Conversely, if implied volatility falls from 20% to 19%, the estimated premium would drop to $11.20.

This is an estimate, not a guarantee. The price of the underlying asset, time value, interest rates, and other Greeks can shift simultaneously, so the actual premium move will likely differ from what Vega alone suggests.

How Traders Can Use Vega

Vega gives traders a way to assess how sensitive their options position is to changes in implied volatility. It can help in choosing better contracts and building appropriate trade plans. Common uses include:

Assessing Volatility Exposure

This shows whether a position has positive or negative exposure to implied volatility. A positive-Vega position benefits from rising implied volatility, while a negative-Vega position can benefit from falling implied volatility.

Comparing Option Contracts

Traders can compare Vega across strikes and expiration dates to identify contracts with higher or lower volatility sensitivity.

Evaluating Volatility-Based Strategies

Traders anticipating changes in implied volatility can use Vega to gauge premium sensitivity — useful for volatility-focused strategies that don’t depend on price direction.

Managing Multi-Leg Positions

Vega can be summed across individual legs to evaluate the volatility exposure of a multi-leg strategy. For example, a position with +0.50 Vega combined with one at -0.30 Vega nets to approximately +0.20 Vega.

Monitoring Portfolio Risk

Tracking total portfolio Vega helps traders understand how the whole book reacts to volatility shifts. A portfolio with high positive or negative Vega can see substantial value changes when implied volatility moves.

Relationship Between Vega and Options Strategies

The table below shows the relationship between Vega and common options strategies:

Options Strategy Typical Vega Exposure Impact of Rising Implied Volatility
Long Call Positive Generally beneficial
Long Put Positive Generally beneficial
Short Call Negative Generally unfavorable
Short Put Negative Generally unfavorable
Long Straddle Strong Positive Generally beneficial
Long Strangle Positive Generally beneficial
Short Straddle Strong Negative Generally unfavorable
Short Strangle Negative Generally unfavorable


Actual Vega exposure will vary depending on strikes, expirations, and other contract characteristics.

Mistakes to Avoid When Trading Vega Options

Vega offers valuable information, but it shouldn’t be analyzed in isolation. Traders often misjudge an option’s risk by focusing on a single Greek while ignoring the broader pricing picture. Common mistakes include:

  •       Confusing Vega with volatility: Vega indicates sensitivity to implied volatility — it isn’t the volatility figure itself.
  •       Ignoring the underlying price: An option’s premium can shift from implied volatility alone, even if the underlying asset isn’t moving.
  •       Treating Vega as a guarantee: Vega assumes every other input stays constant, which rarely holds true in live markets.
  •       Overlooking portfolio-level Vega: Individual positions may show small Vega values, but combined across a portfolio, the exposure can become significant.

Delta, Gamma, Theta, implied volatility, and underlying price should all be considered alongside Vega, not in place of it.

Conclusion

Vega shows how changes in implied volatility can affect option prices. Its significance grows with time to expiration and with higher sensitivity to volatility shifts. Analyzing the Vega of each trade and strategy can help surface potential risks, but vega options analysis should be one part of a broader options analysis, not a standalone signal.

If you want to sharpen your options knowledge with actionable insights, market perspective, and educational resources, visit MySPYOptions for options trading education and market insight.

FAQs

  1. What is Vega in options?

Vega shows how much an option’s premium may change for every 1 percentage-point move in implied volatility, assuming other factors stay constant. The higher the Vega, the more sensitive the option is to implied volatility changes.

  1. Is higher Vega good for options traders?

Not always. High Vega can benefit traders holding long option positions when implied volatility rises, but it can also raise risk if implied volatility falls. It depends on the trader’s position and outlook.

  1. Is Vega positive for calls and puts?

Yes, Vega is positive for both long call and long put positions. Their premiums rise with increasing implied volatility and fall as implied volatility declines.

  1. What happens to Vega when implied volatility rises?

Premiums on long options tend to increase. However, Vega itself can shift with market conditions, moneyness, and time to expiration, so it shouldn’t be treated as a fixed number.

  1. Which options have the highest Vega?

At-the-money options typically carry the highest Vega. Longer-dated options also tend to have higher Vega, since there’s more time for volatility changes to affect the premium.

  1. What’s the difference between Vega and Delta?

Delta measures sensitivity to the underlying asset’s price movement, while Vega measures sensitivity to implied volatility changes. Together, they help traders assess different dimensions of options risk.


Categories
Finance Options Trading

Best Options Trading Tools for Beginners & Pros

The right options trading tools depend less on your experience level and more on which job you’re trying to do — placing trades, finding candidates, sizing risk, or reviewing what worked. Most “best tools” roundups mix brokers, screeners, and calculators into one undifferentiated list, which leaves beginners overwhelmed and pros without a clear upgrade path.

This guide organizes options trading tools by the actual job they solve, gives you a decision matrix for building a stack that matches your experience level, and shows what a minimal, practical toolkit looks like if your focus is SPY and QQQ rather than the entire market.

What Counts as an Options Trading Tool?

In short: An options trading tool is any software that helps you find, analyze, size, execute, or review an options trade. That spans five distinct jobs — execution, discovery, analysis, risk sizing, and review — and no single platform does all five equally well.

Most traders start with just a broker’s built-in platform and gradually add specialized tools as their strategies get more specific. The mistake isn’t using a broker platform alone; it’s assuming that one tool covers every job in the process.

The 5 Categories of Options Trading Tools You Actually Need

Bottom line: Every options trading tool on the market fits into one of five jobs — execution, discovery, analysis, risk management, or performance review. Knowing which job a tool solves prevents you from paying for overlapping features or missing a category entirely.

Category Job It Solves Common Examples
Execution platforms Placing and managing trades thinkorswim, tastytrade, Interactive Brokers, Fidelity
Discovery tools (screeners/scanners) Finding contracts or setups matching your criteria Broker-built screeners, Barchart, dedicated flow scanners
Analysis tools Modeling payoff diagrams, Greeks, and probability OptionStrat, platform-native P/L visualizers
Risk & position sizing tools Calculating position size, Stop-Loss levels, and Risk-to-Reward Ratio Broker margin calculators, spreadsheet models
Performance review tools Journaling trades and analyzing what worked Trade journal software, broker trade history exports

Key takeaway: A complete toolkit touches all five categories. Most beginners over-invest in execution platform features (chasing the “best broker”) while skipping performance review entirely — and review is often what separates a trader who improves from one who repeats the same mistakes for years.

Building Your Tool Stack: A Decision Matrix by Experience Level

Rather than adopting every tool a “best of 2026” list recommends, match your stack to your actual stage. Adding pro-level complexity too early usually slows a beginner down; staying with beginner tools too long caps a pro’s edge.

Stage Execution Discovery Analysis Risk Sizing Review
Beginner Broker’s standard platform with paper trading Broker’s built-in screener only Broker’s native payoff diagram tool Simple percentage-of-account rule Manual notes after each trade
Intermediate Broker platform + real-time Greeks Broker screener + one dedicated free tool (e.g., Barchart) Dedicated payoff visualizer (e.g., OptionStrat) Spreadsheet-based position sizing model Basic trade journal software
Pro / Active Platform with advanced order types and multi-leg execution Real-time flow scanner + custom saved screens Multi-leg strategy builder with IV Rank overlays Automated risk dashboards, portfolio-level Greeks Structured journal with tagged strategy performance

In short: Progression through this matrix should follow your strategy complexity, not your account size. A trader running the same covered call strategy for three years doesn’t need pro-tier discovery tools just because their account has grown — but a beginner running multi-leg iron condors from day one is already under-tooled with beginner-stage discovery alone.

Comparing Popular Options Trading Tools by Category

Here’s how well-known tools map onto the five categories above. This isn’t a ranked “best overall” list — the right fit depends on your stage and strategy, not a single winner.

  • thinkorswim (Schwab) — Execution and analysis. Strong native Option Hacker screener, paper trading, and a deep glossary linked directly to live metrics like Implied Volatility and the options Greeks.
  • tastytrade — Execution and discovery. Built around options-first workflows with an integrated screener and embedded educational context on the trade ticket itself.
  • Interactive Brokers — Execution for advanced traders. Offers a Probability Lab and Volatility Lab for traders who need institutional-grade analytics alongside global market access.
  • Barchart — Discovery. A free, web-based screener useful for beginners learning which filters (Open Interest, Volume, Implied Volatility) matter before committing to a paid tool.
  • OptionStrat — Analysis. Purpose-built for visualizing payoff diagrams and probability of profit across single- and multi-leg strategies before risking capital.
  • Dedicated flow/scanner platforms — Discovery, for pros specifically watching unusual options activity as a directional signal rather than filtering by fixed criteria.

Bottom line: No single platform excels at all five jobs. Most experienced traders run two or three tools together — one for execution, one for discovery, and a lightweight review process — rather than searching for one app that does everything.

A Minimal SPY & QQQ Tool Stack

Most tool roundups are built for traders scanning the entire market across thousands of tickers. If your focus is exclusively SPY and QQQ, a much smaller stack does the job — and paying for whole-market breadth is often wasted spend.

Practical workflow for a SPY/QQQ-focused trader:

  1. Execution: A broker with real-time Greeks and paper trading for practice (thinkorswim or tastytrade both work well here).
  2. Discovery: A single saved screen per ticker, since the Invesco QQQ Trust (QQQ) and SPDR S&P 500 ETF Trust (SPY) carry different baseline Implied Volatility profiles and shouldn’t share one filter set.
  3. Analysis: A payoff visualizer to confirm max loss, max gain, and breakeven before entering any multi-leg position.
  4. Risk sizing: A simple rule — for example, capping any single position at 1-2% of account value — checked against your calculated Risk-to-Reward Ratio.
  5. Review: A basic log of entry criteria, exit reason, and outcome, reviewed weekly rather than after every single trade.

Mini example (hypothetical, for illustration only): A trader running weekly SPY put credit spreads doesn’t need a $100/month flow scanner tracking dark pool activity across the whole market. A broker’s built-in screener, one saved filter (30-45 DTE, 0.20-0.25 delta, IV Rank above 40), a free payoff calculator, and a simple spreadsheet journal cover the entire workflow at little to no added cost.

Common Mistakes When Building an Options Trading Toolkit

  1. Chasing the “best broker” instead of the right job fit. A broker with the deepest analytics is wasted on a trader who only needs basic execution and a simple screener.
  2. Skipping performance review entirely. Execution, discovery, and analysis tools get attention; almost nobody journals consistently, even though it’s often the highest-leverage habit for improvement.
  3. Scaling tool complexity with account size instead of strategy complexity. A bigger account doesn’t require pro-tier tools if the strategy hasn’t changed.
  4. Using one filter set for both SPY and QQQ. Their different volatility baselines mean a single IV threshold will misclassify one of the two.
  5. Treating a tool’s output as a finished decision. Any screener result, payoff diagram, or flow alert still needs a check against the underlying’s technical chart, Moving Averages, MACD, or VWAP before you act.

Learn to Use These Tools with Purpose: MySpyOptions

Tools organize information — they don’t teach judgment. Knowing that a broker’s screener returned a 0.20-delta SPY put, or that a payoff calculator shows a favorable Risk-to-Reward Ratio, only matters if you understand how that trade fits your broader plan and risk tolerance.

This is where MySpyOptions fits into the toolkit conversation. Rather than teaching generic options theory across every possible underlying, the platform focuses specifically on practical SPY and QQQ trading — the two most liquid, most heavily traded instruments for retail options traders — so the tools above connect directly to strategies you’ve actually studied rather than abstract examples. Structured, strategy-specific education tends to build consistency faster than assembling tools without a framework for using them.

Why Choose MySpyOptions

Buying more tools rarely fixes inconsistent trading. MySpyOptions is built around three things that actually move the needle:

  • Focused curriculum on SPY and QQQ, so lessons map directly to the minimal tool stack most retail traders actually need.
  • Practical strategy walkthroughs that connect screener output, payoff diagrams, and position sizing into one coherent process instead of disconnected tools.
  • Trader support from experienced traders and a community reviewing the same setups — without exaggerated promises about tools or performance.

The goal is turning a pile of tools into a repeatable process.

Key Takeaways

  • Options trading tools fall into five jobs: execution, discovery, analysis, risk sizing, and review. A complete toolkit touches all five, not just execution.
  • Match tool complexity to your strategy’s complexity, not your account size or a generic “best of 2026” ranking.
  • No single platform does all five jobs well — most traders run two or three tools together.
  • If you only trade SPY and QQQ, a minimal five-step stack usually beats an expensive, whole-market platform.
  • Tools organize information; they don’t replace risk management, chart review, or a structured process for interpreting what they show you.

Frequently Asked Questions

What are the most important options trading tools for beginners? Beginners generally need just three things to start: a broker platform with paper trading, that broker’s built-in screener, and a simple risk-sizing rule like capping any position at 1-2% of account value. More advanced tools can wait until strategy complexity actually requires them.

Do I need a paid options trading platform, or is a free one enough? For most retail traders, a broker’s free, built-in tools (screener, payoff diagrams, paper trading) cover execution, discovery, and analysis. Paid, dedicated tools become worthwhile once your strategy specifically requires features your broker doesn’t offer, like real-time flow data or advanced portfolio-level Greeks.

What’s the difference between an options screener and a trading platform? A trading platform executes and manages trades; a screener filters the options chain by criteria like delta, implied volatility, and open interest to help you find candidates before you trade. Many platforms include a basic screener, but dedicated screening tools often add deeper filters.

Should I use the same tools for SPY and QQQ that I’d use for individual stocks? Not entirely. SPY and QQQ have different baseline Implied Volatility and are driven more by macro events than single-company earnings, so a screener calibrated for individual-stock earnings proximity is less useful here than one accounting for Federal Reserve announcements and broad market catalysts.

Why is trade journaling considered a trading tool? Because performance review is one of the five core jobs any complete toolkit needs to cover. Reviewing entry criteria, exit reasoning, and outcomes systematically is often what separates traders who improve over time from those who repeat the same mistakes.

Can I trade options successfully with just a broker’s built-in tools? Yes, for many strategies. A broker’s native screener, payoff visualizer, and paper trading account cover the essential execution, discovery, and analysis jobs. Dedicated third-party tools add depth but aren’t required to start trading responsibly.