When considering options, investors analyze Greeks such as Delta, Gamma, Theta, and Vega. However, there is another Greek that can have a strong impact on the price of the option depending on interest rate changes: Rho.
Rho shows how sensitive the price of an option is to changes in the risk-free interest rate. Its effect becomes visible when time to expiration is large. Thus, knowing Rho allows assessing the position better under changed monetary conditions. In this article, we will look into Rho options, how Rho works, and why it is important for various options strategies.
What is Rho?
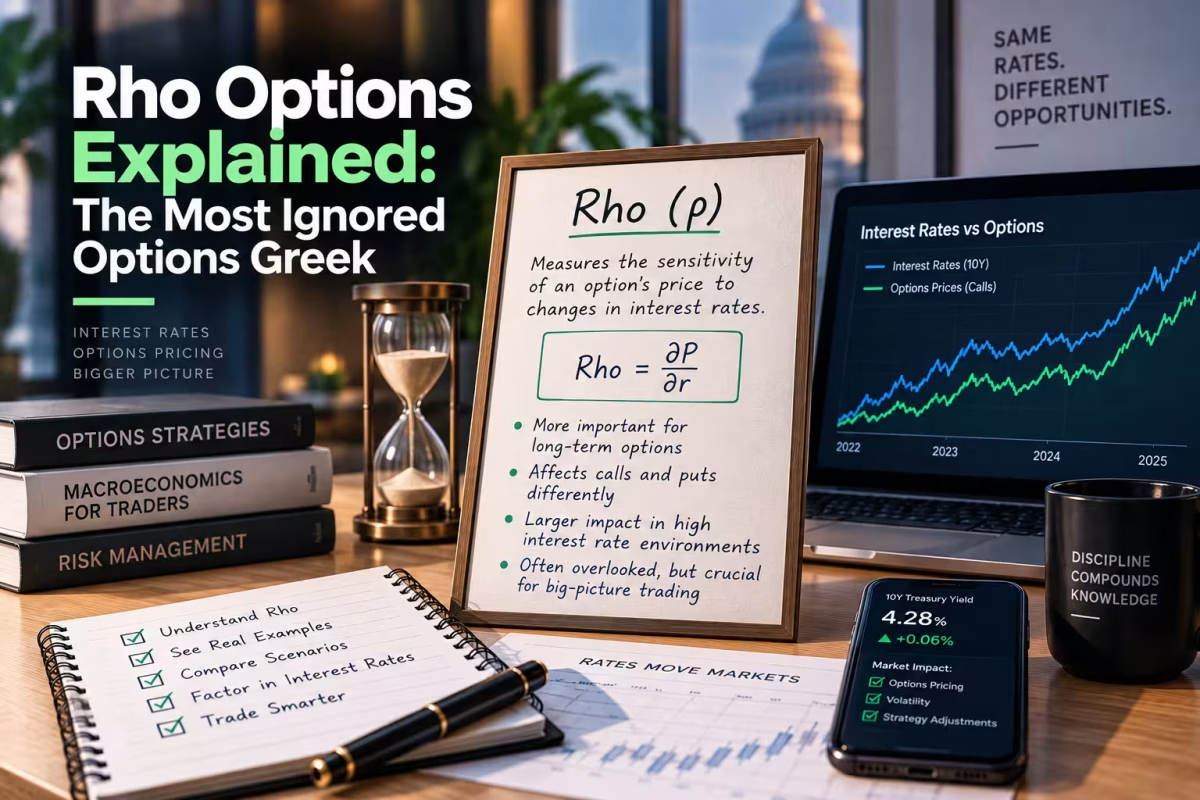
Rho is the measure that shows how much the theoretical price of an option may change in case of a 1% change in the risk-free interest rate. It isolates the effect of interest rates while assuming other pricing factors remain unchanged.
For example, if the Rho of an option is 0.30, its price will theoretically increase by $0.30 per share in case of a 1% increase in the risk-free interest rate and will fall by this amount in case of a 1% decrease.
The risk-free rate usually refers to government securities and, specifically, to Treasury rates in the United States. Traders can also take into account the interest-rate situation in the country when assessing longer-term positions.
Rho is often ignored since interest rate changes usually influence the price of an option less than changes in the price of the underlying asset or in the implied volatility. However, this does not mean that it is not important.
Why is Rho Called the Most Overlooked Options Greek?
The reason Rho is usually ignored is that many retail options trades have short expiration dates. Weekly and short-dated options have low interest rate exposure.
Meanwhile, longer-dated options have more exposure to the effects of financing and discounting, as the process takes more time. Therefore, even a minor change in the interest rate may become more important in the long term.
That is why Rho options are important when:
- Interest rates change fast
- Monetary policy of the Central Bank changes
- Traders hold long-dated options
- The positions are based on substantial capital
- Investors trade with the help of LEAPS and other long-term options
- Interest-rate expectations have a great influence on market sentiment
It is important to keep in mind that Rho is not always equally important in every trade. Its importance largely depends on the expiration, type of option, moneyness, and the rate situation.
How Does Rho Affect Calls and Puts?
There is an important difference between the Rho of calls and the Rho of puts. Call options usually have positive Rho. When interest rates increase, the theoretical value of a long call will grow if other factors remain the same. The increased rates decrease the present value of the strike price to be paid in the future.
Meanwhile, put options usually have negative Rho. When interest rates increase, the theoretical value of a long put will decrease. The opposite effect will occur in the case of decreasing rates.
For example, a call with a Rho of 0.25 could theoretically gain $0.25 per share from a 1 percentage-point increase in the relevant interest rate. A put with a Rho of -0.25 could theoretically lose $0.25 per share under the same assumption. These figures show the sensitivity but not guaranteed changes in the market price.
The Effect of Time to Expiration on Rho
Time to expiration is one of the main factors that determine Rho sensitivity. An option with expiration in several days has not much time left for interest-rate changes to have an influence on it.
Meanwhile, options with expiration in several months or in years have much more time for the influence. That is why longer-dated options usually have greater Rho. This effect is particularly important for LEAPS.
Traders who hold long-term calls or puts cannot ignore Rho because it may mean ignoring some part of the interest-rate exposure of the position. While under stable interest-rate conditions the effect may be modest, it can become much more important in case of monetary policy changes.
How Does Moneyness Influence Rho?
Rho options also vary according to an option’s moneyness. The relationship between moneyness and Rho can help explain how interest rates affect options differently, as discussed below.
In-the-money options
ITM options usually have greater Rho sensitivity than OTM options. Their intrinsic value and increased probability of exercising can make interest rate changes more important.
So, a deeply in-the-money call can react more strongly to changes in interest rates than a comparable out-of-the-money call.
At-the-money options
ATM options usually lie between ITM and OTM options regarding Rho sensitivity. Pricing of ATM options includes both intrinsic and time value, among other factors such as volatility.
Rho remains important, especially for options with longer expiries.
Out-of-the-money options
OTM options usually have lower Rho sensitivity. They depend heavily on time to expiration and volatility rather than on intrinsic value.
Nevertheless, even low sensitivity does not equal zero sensitivity. Large positions and longer expirations can make the effect worth monitoring.
A Simple Rho Options Example
Suppose a call option is priced at $10 with the relevant risk-free interest rate of 5%.
Suppose the rate rises to 6%, while other pricing variables remain unchanged. If the theoretical value increases to $10.50, then the price moves by $0.50 per share for a 1 percentage-point change in the interest rate.
Hence:
- Rho (per share) = Change in option value ÷ Change in interest rate
- Rho (per share) = $0.50 ÷ 1 percentage point = $0.50 per 1% rate change
With a standard 100-share contract multiplier, that translates to $0.50 × 100 = $50 in theoretical dollar value per contract, for each 1 percentage-point move in interest rates.
This example ignores the complex process of actual pricing. Actual prices are influenced not only by the risk-free interest rate but also by other factors, such as the price of the underlying asset, volatility, time decay, dividends, liquidity, and other factors.
How to Calculate Rho
Rho is a partial sensitivity of an option’s value to the risk-free interest rate. It is represented as follows:
ρ = ∂V / ∂r
Where:
- V is the option’s value
- r is the interest rate
- ρ is the sensitivity of option value to the interest rate
There are more complicated equations used in professional pricing models. According to the Black-Scholes model, Rho depends on factors such as strike price, time to expiration, volatility, and the ratio between the price of the underlying asset and the strike.
Usually, traders do not calculate Rho options themselves, options trading and analytics software provides this measure.
How Can Rho Be Used for Trading in Options Strategies?
Rho can be of significant help in the context of a whole risk-assessment system, but not in isolation. Below are some practical ways traders can use Rho across different options strategies.
- Assessment of Long-Dated Positions
If the trader holds a long-dated call or put, they can monitor Rho together with Delta, Vega, and Theta, giving a full picture of the position’s sensitivities.
- Assess Interest-Rate Scenarios
When monetary policy is expected to change, Rho helps estimate the direction of possible interest-rate exposure of the option.
In the case of positive Rho, the long call benefits from an interest-rate increase, while the opposite happens with the long put.
- Comparison of Different Expirations
When comparing two options with otherwise equal factors, Rho shows how much additional interest-rate exposure comes from choosing a longer expiration.
This approach is particularly useful when deciding between short-term and long-term options.
- Construction of Portfolio Hedges
Portfolio managers can consider Rho while building hedges using long-term options. Factoring in Rho can help surface exposures that other Greeks don’t capture.
- Combining Rho with Other Greeks
Each Greek considers a different aspect of an option’s risk.
Delta shows sensitivity to changes in the price of the underlying asset; Gamma shows changes in Delta; Theta shows the effect of time decay; Vega shows sensitivity to changes in implied volatility; and Rho shows interest-rate sensitivity.
When Should Traders Pay More Attention to Rho?
While long expiration and changing interest rates usually make Rho more important, traders should also take into account expiration, position size, and other market factors. The following situations can make Rho more relevant:
- Long-dated options can have greater sensitivity to interest-rate changes.
- Changing interest rates can increase the practical importance of Rho.
- Major central bank decisions may affect options with higher Rho exposure.
- Large positions can make small Rho changes more financially significant.
- LEAPS and other long-term strategies may require closer attention to Rho.
- Interest-rate-sensitive assets can make Rho more relevant to a trading strategy.
- Portfolio risk management can benefit from understanding overall Rho exposure.
- Short-term options may require less attention to Rho when rates remain stable.
Therefore, traders should focus on situations where interest-rate exposure could materially affect the position.
Rho vs Other Options Greeks
The table below compares the primary sensitivity of each Greek and the situations in which it becomes more relevant.
| Greek | Primary Sensitivity | Generally More Relevant When |
| Delta | Underlying price | The underlying moves |
| Gamma | Change in Delta | Positions approach expiration |
| Theta | Time decay | Time passes |
| Vega | Implied volatility | Volatility changes |
| Rho | Interest rates | Rates and longer expirations matter |
This comparison shows why Rho can remain hidden in short-term trading. Other Greeks often create larger day-to-day price effects. Still, Rho completes the broader picture of option-price sensitivity.
Conclusion
Although Rho is not as popular as other Greeks, it can reveal important interest-rate exposure. Its importance increases with long-dated options and changing monetary conditions. Knowing Rho options can help traders evaluate risks that may go unnoticed without considering Delta, Theta, Gamma, and Vega.
For actionable options education, market perspectives, and trading insights, visit MySPYOptions to strengthen your options knowledge and decision-making.
FAQs
- What does Rho mean in options trading?
Rho is the measure that shows how much the theoretical price of an option may change for a 1% change in the risk-free interest rate.
- Is Rho positive for call options?
Yes, call options generally have positive Rho, meaning the theoretical price of a call tends to increase as interest rates rise.
- Which options are most affected by Rho?
Long-dated options, particularly ITM contracts, generally show greater Rho sensitivity than short-dated or OTM options.
- Should traders use Rho alone when making decisions?
No, Rho should be considered alongside Delta, Gamma, Theta, Vega, expiration, moneyness, and broader market conditions.